🐋 ACMR $7.4M Bullish Call Blitz — A Desk Bet the Momentum Train Keeps Rolling
📅 June 12, 2026 | 🔥 Unusual Activity Detected
✅ Updated 2026-06-15: Next-day OPRA OI confirms the open on the carry-forward leg — the Jun-18 $100 call rose 92 → 4,402 (Δ +4,310 ≈ the 4,276 traded). Fresh bullish open confirmed. The $86/$89 0DTE legs expired Friday, so they have no next-day OI.
🎯 The Quick Take
At 09:43:03 this morning, a desk routed a ≈$7.4M multi-leg auction on ACM Research (ACMR) — buying calls at three strikes simultaneously with the stock trading ≈$93.53, fresh off a blistering +15% jump the prior session. Two of the three legs expire today (0DTE), and one runs to June 18. This is not a patient LEAP bet — it's a high-conviction, short-fuse trade riding the wave from Roth Capital's $70→$100 price-target raise and the China semiconductor localization story. Someone paid up aggressively with the clock ticking.
📊 Company Overview
ACM Research (ACMR) makes the machines that clean semiconductor wafers — not glamorous, but absolutely critical to building every advanced chip:
- Market Cap: ≈$5–6B (Information Technology / Semiconductors & Semiconductor Equipment)
- What they do: ACM designs and sells wafer-cleaning, electroplating (ECP), furnace, and advanced-packaging tools used by chipmakers. Their proprietary SAPS and TEBO cleaning technologies are qualified at SK Hynix and China's YMTC/CXMT memory fabs — precisely the fabs building the next generation of HBM (high-bandwidth memory) chips that power AI.
- The big picture: ACM is the dominant domestic semiconductor equipment provider in China. When U.S. export controls block Lam Research, Applied Materials, and Tokyo Electron from selling into China, ACM fills the gap. It's structural tailwind, not a trade.
- Recent performance: Q1 2026 revenue $231.3M, +34% YoY, with gross margin recovering to 46.5%. The stock soared ≈15% on June 11 after Roth Capital raised its target from $70 to $100 — and today's desk loaded up right at the open.
💰 The Option Flow Breakdown
The Tape — June 12, 2026 @ 09:43:03: 🤝 Multi-Leg Auction
| Time | Side | C/P | Strike | Exp | Volume | OI | Size | Premium | Spot | Opt Px | Symbol |
|---|---|---|---|---|---|---|---|---|---|---|---|
| 09:43:03 | BUY | CALL | $86 | 2026-06-12 | 4,300 | 4,400 | 4,276 | $3.6M | $93.53 | $8.44 | ACMR20260612C86 |
| 09:43:03 | BUY | CALL | $89 | 2026-06-12 | 4,300 | 4,400 | 4,276 | $2.6M | $93.53 | $5.98 | ACMR20260612C89 |
| 09:43:03 | BUY | CALL | $100 | 2026-06-18 | 4,300 | 92 | 4,276 | $1.2M | $93.53 | $2.83 | ACMR20260618C100 |
Total: ≈$7.4M across three legs
Flow type: 🤝 Multi-Leg Auction — all three legs printed simultaneously through a facilitated exchange price-improvement auction. This is a worked complex order where a broker coordinated both sides of the trade off the open book. Not a panicked lit sweep — a deliberate, structured entry.
✅ RESOLVED — Next-Day OI Confirms the Open (2026-06-15)
| Leg | Pre-print baseline (EOD 2026-06-11) | Resolving (EOD 2026-06-12) | Δ | Verdict |
|---|---|---|---|---|
| Jun-18 $100C | 92 | 4,402 | +4,310 (≈ the 4,276 traded) | OPEN — BTO confirmed |
| Jun-12 $86C (0DTE) | 4,400 | — expired Friday — | n/a | Unresolvable by OI |
| Jun-12 $89C (0DTE) | 4,400 | — expired Friday — | n/a | Unresolvable by OI |
The Jun-18 $100 call opened fresh — open interest jumped from 92 to 4,402, a rise of +4,310 that matches the 4,276 contracts traded. That confirms the directional bullish BTO read on the carry-forward leg. The $86 and $89 legs expired at Friday's close (0DTE), so OPRA publishes no next-day OI for them — their open/close cannot be resolved from OI and we do not guess.
🤓 What This Actually Means — Plain English
Let's break this down the way you'd explain it over coffee.
A desk just bought ≈$7.4M worth of call options on ACMR across three different strikes, all at the same second, all expiring very soon. Two of the three expire TODAY (the $86 and $89 calls). One runs until June 18 (the $100 call).
Why would anyone spend $7.4M on options that expire in hours?
Because those 0DTE calls are already deep in the money. With ACMR trading at ≈$93.53:
- The $86 call has ≈$7.53 of intrinsic value (stock price minus strike). At $8.44, almost all of the premium is real value, not time value. This is more like a leveraged stock substitute than a lottery ticket.
- The $89 call has ≈$4.53 intrinsic value. At $5.98, again — mostly real value.
- The $100 call (Jun-18) is the speculative leg: ACMR needs to push above $100 for this to be in the money. At $2.83, this is the "moonshot" slice of the structure.
The structure tells a story: Two deep-ITM 0DTE calls for immediate, high-delta exposure today — essentially a leveraged long position that expires at the closing bell. Plus one near-dated OTM call reaching toward the Roth $100 target as the "what if this keeps running" leg.
Order type interpretation: The $86 and $89 legs are provisionally ⏳ BTO (Buy to Open), subject to tomorrow's OI confirmation. The $100 Jun-18 leg is effectively confirmed BTO given size ≫ prior OI. The overall structure reads as a directional bullish play — not a hedge, not a spread, not a premium collector's game.
Breakeven math:
- $86C breakeven: $86 + $8.44 = $94.44 (≈1% above spot today)
- $89C breakeven: $89 + $5.98 = $94.98 (≈1.5% above spot)
- $100C breakeven: $100 + $2.83 = $102.83 (≈9.9% above spot, by June 18)
The desk needs ACMR to hold above ≈$94.44–$94.98 by today's close to profit on the 0DTE legs. On the $100 call, they need a further push to ≈$102.83 by June 18. That is exactly where Roth Capital's revised $100 target sits — the Jun-18 $100C is essentially a direct bet that the analyst upgrade becomes a self-fulfilling price milestone within the week.
📈 Technical Setup / Chart Check-Up
YTD Performance
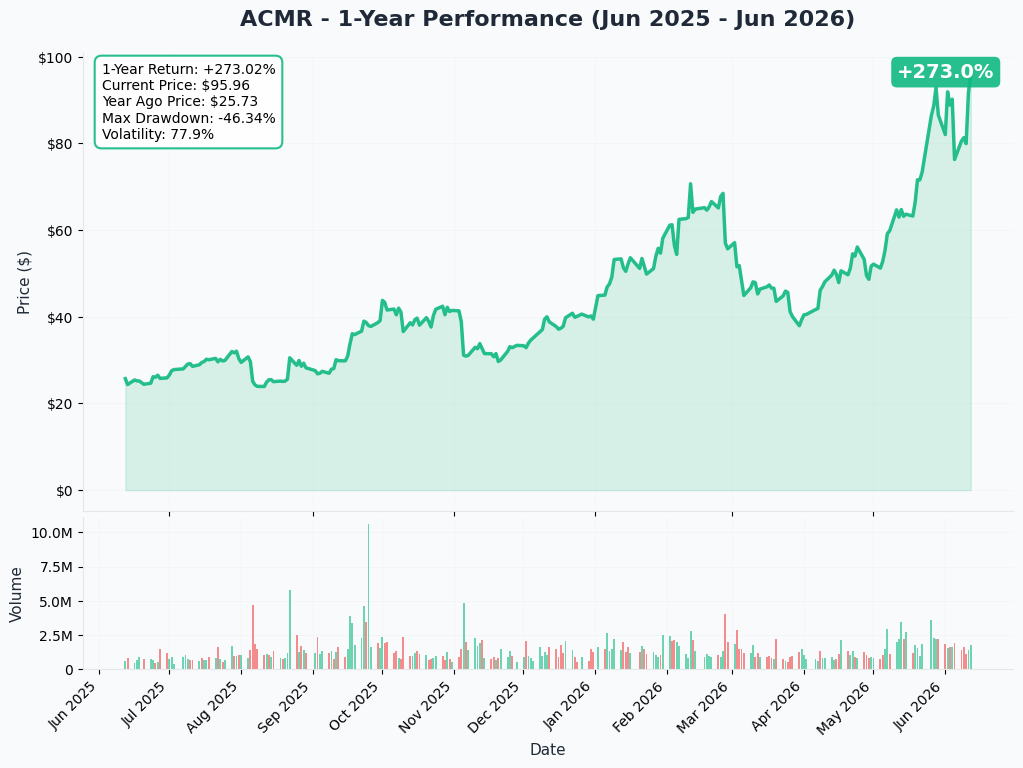
ACMR has been one of the hottest names in semiconductors in 2026. The stock has surged ≈90% over ≈2.5 months into late May before pulling back, then re-accelerated sharply on June 11 on the Roth upgrade. The YTD move reflects a market that is repricing ACM Research as a structural AI/HBM memory capex beneficiary — not just a China clean-equipment play.
Key observations:
- 📈 Up dramatically YTD, with the June 11 gap-up adding another +15% in a single session
- 🎯 The stock opened ≈$84 on June 11 and closed ≈$91.70 — a textbook breakout on the upgrade catalyst
- ⚡ Today's ≈$93.53 is the stock continuing to trade above yesterday's close, holding the breakout
Gamma-Based Support & Resistance
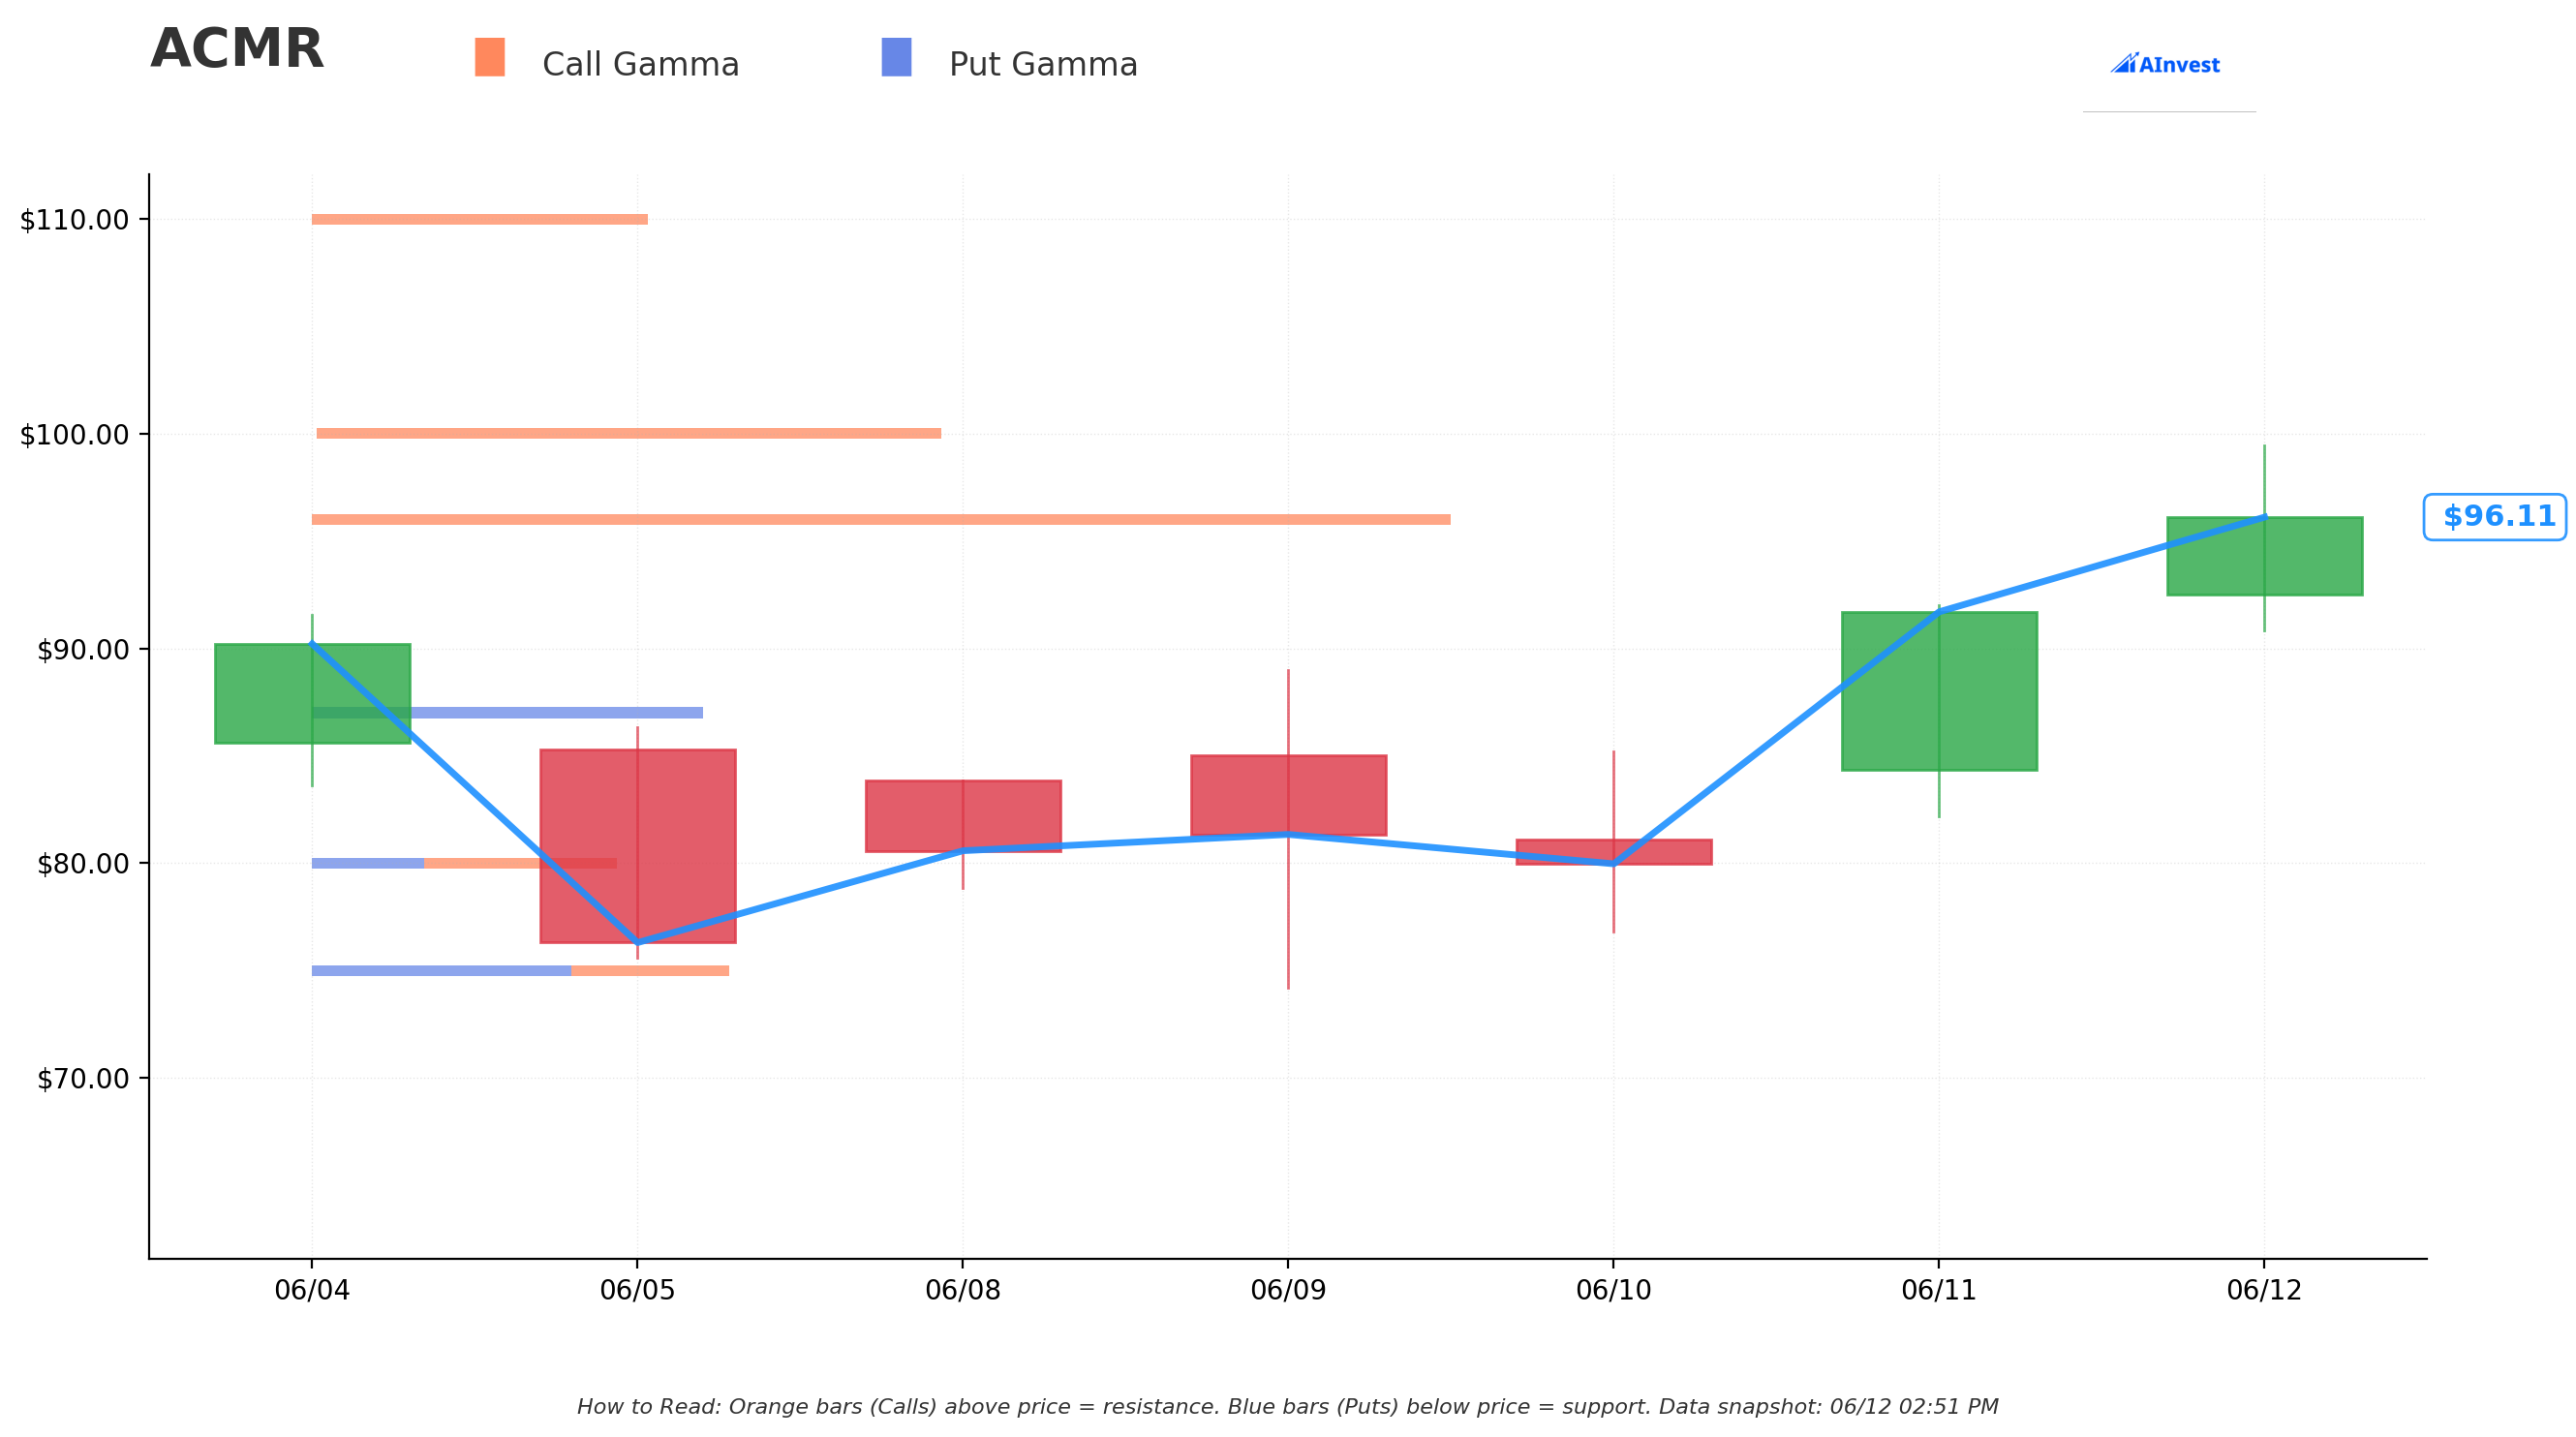
ACMR is a thinly-optioned mid-cap, and the gamma structure reflects that — there are no massive, fixed "walls" the way you'd see on a mega-cap like AAPL or SPY. That said, the gamma exposure map does show meaningful clusters at a handful of strikes:
🟠 Resistance / Magnetic Levels (Call Gamma Above Price):
- $96 — The Dominant Call Gamma Strike. This is the single largest gamma concentration in the entire chain (net GEX ≈0.524 — nearly 2x the $100 level below). Market makers are long a significant amount of gamma here, meaning they will hedge by selling stock as price rises toward $96 and buying as it dips. Think of this as a gravitational magnet — the stock will be pulled toward $96 and may struggle to move cleanly through it without a catalyst. The good news: ACMR is already trading right at $96; holding above is the first test.
- $100 — Second-Largest Call Gamma Level. Net GEX ≈0.264. This is also exactly where the Roth price target sits and where the Jun-18 $100C is struck. A sustained break above $100 would be a significant technical development and would trigger further dealer hedging (buying) to push the level.
- $110 — Lighter Resistance Further Out. Net GEX ≈0.141. Within the options market's own probability cone for June OPEX.
🔵 Support Levels (Put Gamma Below Price):
- $87 — Meaningful Put Gamma Support. Net GEX ≈−0.161 (put-dominated). This zone acts as a floor: dealers will hedge by buying stock as price falls toward $87, providing cushion. This is also close to the $86 and $89 call strikes from today's trade — interesting convergence.
- $80 — Secondary Support. Lighter put gamma further below; less relevant for today's trade but the broader floor if a selloff materializes.
- $75 — Deep Support. Thin gamma zone; more of a last resort level than active support.
Translation for traders: ACMR is essentially sitting on top of its biggest gamma wall right now ($96). The stock will likely grind around $94–$98 while it digests the gamma. A catalyst-driven push above $100 would be the event that breaks the gravitational hold and could accelerate quickly toward $110.
Implied Move Analysis
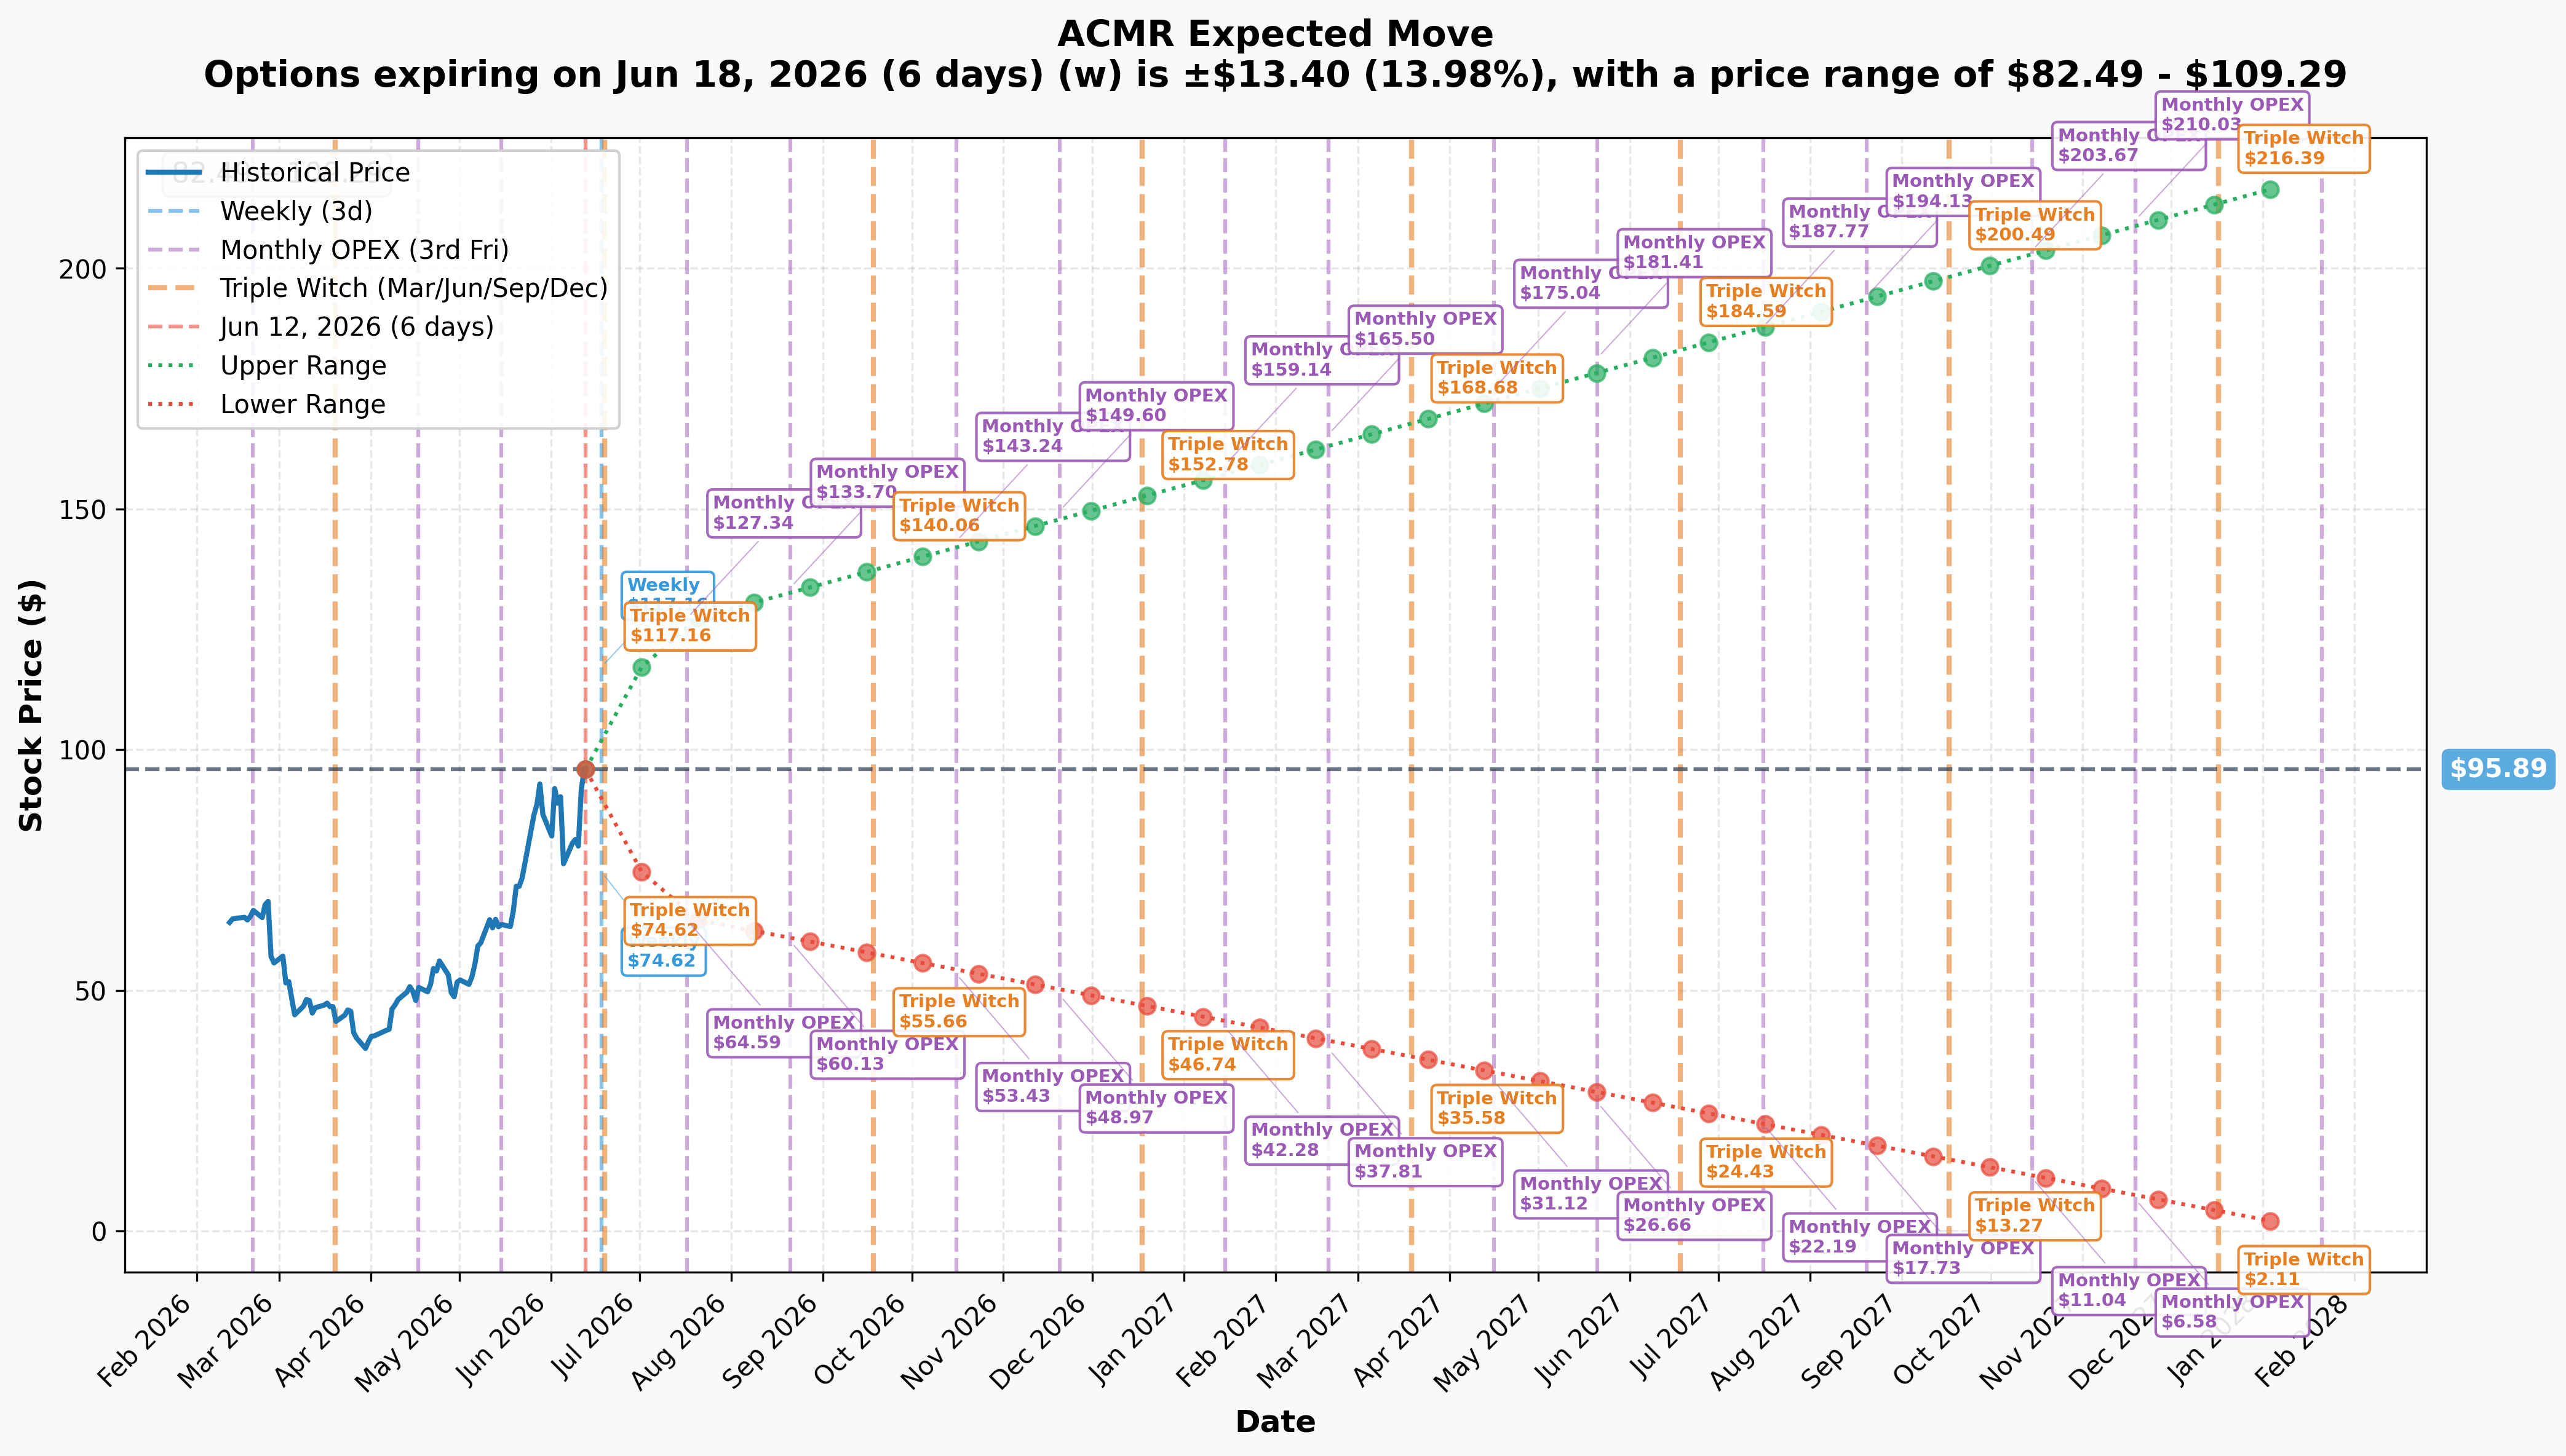
The options market is pricing in very high volatility for ACMR — this is a momentum stock after a +15% session, and IV is elevated:
- 📅 Weekly (exp 2026-06-18, 6 days): ±$13.40 (±13.98%) → Range $82.49 – $109.29
- 📅 Monthly OPEX (exp 2026-07-17, 35 days): ±$30.95 (±32.28%) → Range $64.94 – $126.84
- 📅 LEAP (exp 2028-01-21): ±$123.51 (±128.81%) → Range $0 – $219.40
A ±32% monthly implied move means the options market thinks ACMR could reasonably be anywhere between ≈$65 and ≈$127 by the July OPEX. That's a wide range — and a direct reflection of how volatile and China-news-sensitive this name is.
For the trade at hand: the weekly range of $82.49–$109.29 is the relevant window for the Jun-18 $100C. The $100 strike sits comfortably inside the options market's own upper probability cone for this week. If the momentum holds, the market is saying ≈$100+ is achievable in the next six days — which is why the desk bought it.
🎪 Catalysts
Already Happened (Fueling the Move)
Roth Capital Raised Target $70 → $100, Buy — Early June 2026 📈 Roth cited strong semiconductor demand and improving memory markets, pushing the stock +15% on June 11. With most analyst targets still sitting at $70–74 (stale, pre-run), Roth's $100 is now the freshest and most aggressive target on the street — and the Jun-18 $100C is a direct expression of "Roth is right."
Q1 2026 Earnings Beat — May 8, 2026 💰 Revenue $231.3M, +34% YoY, beating ≈$217.8M consensus by ≈6%. Shipments surged +53.6% YoY to $240.7M — a leading indicator since shipments convert to recognized revenue in subsequent quarters. Gross margin recovered to 46.5%, and FY2026 guidance was reiterated at $1.08–1.175B.
Advanced-Packaging Order Wins (2026) 🏭 ACM announced multiple wafer-level system orders from a Singapore-based OSAT, a North America technology customer, and a panel-level vacuum cleaning order for a packaging manufacturer outside mainland China. This is the ex-China diversification narrative taking its first real steps.
AI/HBM Memory Capex Tailwind — Ongoing 🤖 According to SemiAnalysis, ACM is now qualified at both SK Hynix and YMTC for cleaning and ECP tools in HBM production. As SK Hynix ramps HBM4 capacity through 2026–2027 and China memory makers (CXMT, YMTC) continue to localize, ACM's tools are embedded in the critical path. This is why the stock was cited as up ≈90% in ≈2.5 months by late May 2026.
China Backlog Hit $1.27B — Sep 2025 Reference 📦 ACM Shanghai's cleaning-project backlog reached RMB 9.07B (US$1.27B), +34.1% YoY. A backlog growing faster than revenue means the revenue pipeline is deepening, not thinning.
Upcoming Catalysts (The Window and Beyond)
No Hard Catalyst Before Option Expiry — This Is the Key Risk 🚨 The next confirmed date-specific catalyst is Q2 2026 earnings on August 12, 2026 (before open). That is after both the Jun-12 0DTE legs (expire today) and the Jun-18 $100C. There is no scheduled earnings print, no analyst day, and no confirmed product launch inside the option window. The near-term bull case runs entirely on momentum and the potential for unscheduled order announcements — not a hard catalyst you can mark on a calendar.
Oregon Manufacturing Facility — 2H 2026 🏗️ ACM is targeting operations start at its Oregon facility in the second half of 2026, plus Korea efforts. Milestone updates here would be a positive for the ex-China diversification story.
HBM/Advanced-Packaging Order Announcements — Ongoing Optionality 💡 ACM has a history of press-release order wins that move the stock in a single session. A new SK Hynix, YMTC, or global OSAT win announced before June 18 would be exactly the catalyst that sends the $100C into the money. These are inherently unscheduled.
Q2 2026 Earnings — August 12, 2026 📅 Key metrics to watch: revenue trajectory toward the $1.08–1.175B FY guidance midpoint, gross margin holding ≥46%, and any guidance raise after the Q1 beat. The Jan-18 call will be well past expiry; this is a medium-term watchpost for anyone holding stock.
🎲 4-Reader Interpretation
🚀 YOLO Trader
This is the structure you'd design if you woke up this morning, saw yesterday's +15% surge, and wanted maximum short-term exposure. The 0DTE $86 and $89 calls at today's open are high-delta, fast-moving, clock-ticking. If ACMR pushes higher intraday, those calls multiply fast. If it fades, they go to zero today — no waiting, no theta bleed, it's decided at 4:00 PM ET. The Jun-18 $100C is the "still in the game" leg through next week. If you're playing alongside this desk, size it as pure risk capital — the kind you'd be fine losing entirely. The 0DTE legs are off the board by tonight no matter what.
📊 Swing Trader
The $96 gamma wall is your key level. ACMR is sitting right on top of the biggest gamma cluster in the chain — the stock will likely gravitate to $96 and oscillate while the market digests it. A clean, sustained break and close above $100 (the second gamma level and the Roth target) would be the technical confirmation that the rally has legs. If you want to ride this story, look at the Aug or Sep expiry calls at the $100–$105 strike range — these capture the Q2 earnings on August 12 and give you room for the thesis to develop without the clock pressure of today's 0DTE. Don't chase the 0DTE legs if you missed the open entry.
🛡️ Premium Collector
With IV elevated post-catalyst and no hard catalyst in the window, this is actually an interesting environment for selling short-dated premium on ACMR. The $87 strike has meaningful put gamma support — selling a cash-secured put at the $87–$90 range for the June 18 expiry would collect premium while targeting an entry in a name with strong fundamentals, if it pulls back. The risk: ACM is China-exposed and any U.S.–China headline can gap it down sharply in a single session. Keep position size in check — this is not a "set and forget" situation.
🌱 Entry-Level / Beginner
Here's what happened in plain English. A desk spent ≈$7.4M on "call options" — which are contracts giving them the right to buy ACMR stock at specific prices ($86, $89, and $100). Two of those contracts expire today at market close. Why buy something that expires in hours? Because the stock ($93.53) is already above those first two strike prices ($86 and $89), so the calls already have real value built in. The desk is essentially using the calls as a leveraged way to own ACMR for the day — if the stock keeps climbing, the calls multiply in value; if it falls, they lose the premium. The $100 call (which lasts until June 18) is the longer-dated, higher-risk piece — the stock needs to push above $100 within the next week for that leg to pay off. This is a short-term momentum trade, not a long-term investment.
⚠️ Risk Factors
Options trading involves substantial risk of loss and is not suitable for all investors. The specific risks for this trade and thesis:
No Catalyst Inside the Option Window The single most important risk for the short-dated legs: Q2 earnings is August 12, which is after everything expires. The 0DTE legs live and die by today's price action alone. The Jun-18 $100C needs a ≈6.9% move from current spot in six days — possible given elevated IV, but there is no scheduled news to force that move. Momentum fades without a catalyst.
Stock Is Extended After a Major Run ACMR has surged ≈90% over ≈2.5 months and then added another +15% in a single session. The stock is trading at P/E ≈39, price-to-sales ≈3.6 — not cheap. The valuation embeds significant optimism. A profit-taking wave in a name that has run this far, this fast, would not be unusual.
U.S. Export Controls / Entity List Risk ACM Shanghai and its China operating subsidiaries were added to the BIS Entity List in December 2024. Management says the impact is manageable due to alternative supply chains, but any expansion of export controls — or a new round targeting the ACMR parent — could reset the stock sharply. This is a live, permanent overhang.
HFCAA Listing Tail Risk ACM flags potential HFCA Act-related trading prohibitions in its 10-K filings if PCAOB audit access to its China operations is compromised. This is a low-probability but high-impact tail risk specific to U.S.-listed Chinese-exposed companies.
Customer Concentration Revenue is heavily weighted to a handful of Chinese fabs — YMTC, CXMT, and peers. A slowdown in China localization capex, whether from a domestic economic cooling or policy shift, hits ACM disproportionately hard.
Dilution + Insider Sale The company raised ≈$150M in a direct stock offering at $52 per share earlier in 2026 — dilutive at the price where it was issued (though the stock has since run well above). A company SVP also sold 18,750 shares (≈$1.59M) on June 4, 2026. Neither is a red flag in isolation, but both are worth noting in a momentum name where sentiment can shift fast.
What the OPRA Tape CANNOT Tell Us: We know the mechanism (multi-leg auction), the size (4,276 contracts per leg), the prices, and the direction (all BUY calls). We do not know the buyer's identity, whether this is a standalone bet or part of a hedged portfolio, or their existing ACMR position. We interpret the tape; we do not read minds.
🎯 The Bottom Line
Here's the deal: a desk woke up this morning, saw a semiconductor equipment name that just gapped +15% on an analyst upgrade, and decided to pile in with ≈$7.4M across three call strikes right at the open.
Two legs expire today. One runs to June 18. The structure is clear: ride today's momentum with high-delta in-the-money 0DTE calls, and reach for Roth's $100 target with the Jun-18 OTM leg. The underlying thesis — China localization driving unprecedented backlog growth, HBM memory capex tailwinds at SK Hynix and YMTC, and Q1 shipments running +54% YoY — is real and supported by data. But the trade itself is pure momentum, pure clock, pure risk.
What to watch today:
- 📅 By 4:00 PM ET today: The $86 and $89 calls expire. If ACMR closes above ≈$94.44–$94.98, both legs are profitable.
- 📅 June 18, 2026: The $100C expiry. Stock needs to clear $100 (≈6.9% from today's ≈$93.53) and stay above the $102.83 breakeven for the desk to profit on that leg.
- 📅 June 13 ≈06:30 ET: OPRA OI snapshot for the Jun-18 $100C — expected to jump from 92 to ≈4,300+, confirming the open. ⏳ Come back then for the definitive read.
- 📅 August 12, 2026: Q2 2026 earnings before open — the next hard catalyst for anyone building a longer-dated ACMR position.
If you're watching this from the sidelines: The $96 gamma wall is the price the stock is gravitating toward right now. A clean hold and push above $100 on fresh volume would be the signal the rally has another leg. No catalyst before June 18 means you're betting on pure momentum — size accordingly.
If you're bearish: The run has been extreme. The $87 strike has put-gamma support but below it, the stock could retrace quickly toward $80. Any U.S.–China headlines are the catalyst to watch for that scenario.
A ≈$7.4M short-dated call structure on a China semiconductor equipment name trading at all-time momentum highs — bold, high-conviction, and entirely dependent on the momentum train not hitting the brakes before the options expire.
Disclaimer: Options trading involves substantial risk of loss and is not suitable for all investors. This analysis is for educational and informational purposes only and does not constitute financial advice. Past unusual options activity does not guarantee future returns. The 0DTE $86 and $89 calls expire today (June 12, 2026) and will go to zero if ACMR closes below those strikes — 100% loss of premium is possible. The Jun-18 $100C requires ≈6.9% upside in six days and has a breakeven of ≈$102.83; it too can expire worthless. Open/close classification on the $86 and $89 legs is ⏳ provisional (size ≤ prior OI) and will be resolved by next-day OPRA open interest data. Always conduct your own due diligence and consider consulting a licensed financial advisor before making any trading decisions.
Last updated: June 12, 2026
Last updated: 2026-06-15 — next-day OPRA OI resolved the carry-forward leg (OPEN confirmed); 0DTE legs expired and are unresolvable by OI.