🐋 PYPL $1.7M LEAP Call — Big Money Bets on PayPal's 21-Month Turnaround!
📅 April 20, 2026 | 🔥 Unusual Activity Detected
🎯 The Quick Take
Someone just dropped $1.7 MILLION on a January 2028 LEAP call on PayPal (PYPL) this morning — a long-dated bullish bet that needs the stock to rally 37% just to break even. This isn't a short-term punt; this is a patient, high-conviction wager that new CEO Enrique Lores can reignite PayPal's branded checkout growth while PYUSD stablecoins, agentic commerce with OpenAI/Google/Anthropic, and the new Ads Manager platform reach escape velocity. With 21 months of runway before expiration, this trader is playing the full turnaround story — and paying up to do it.
📊 Company Overview
PayPal Holdings, Inc. (NASDAQ: PYPL) is one of the world's largest open digital payments platforms, processing over $1.8 trillion in annual Total Payment Volume across 439 million active accounts. The company sits in the Financial Services / Fintech sector (SIC: State Commercial Banks — Electronic Payment Processing) and operates three core businesses:
- 💳 Branded Checkout — the iconic PayPal yellow button at merchant checkout (highest-margin, currently under pressure)
- 🏢 Braintree (Unbranded PSP) — enterprise payment rails for Uber, DoorDash, Airbnb (lower-margin, high volume)
- 📱 Venmo — P2P and commerce wallet with ~60M active users, growing fast toward a $2B revenue target by 2027
Current Price: ~$50.67 | Market Cap: ~$45.8B | 52-Week Range: $38.46 – $79.50 | YTD 2026: -18%
💰 The Option Flow Breakdown
📊 The Tape (April 20, 2026)
| Time | Symbol | Side | Type | Expiration | Strike | Volume | OI | Size | Spot | Option Price | Premium |
|---|---|---|---|---|---|---|---|---|---|---|---|
| 10:00:51 | PYPL | BUY (Ask) | Call $62.50 | 2028-01-21 | $62.50 | 2,500 | 605 | 2,500 | $50.67 | $6.82 | $1,700,000 |
🤓 What This Actually Means
This is a Long Call LEAP — a pure bullish directional bet on PayPal's recovery over the next 21 months. Here's the breakdown:
- 💸 $1.7M in total premium paid at the Ask — the buyer paid up, which means they wanted in and didn't wait for a fill
- 📏 Vol/OI of 4.13x — over 4x the existing open interest opened fresh in one block, signaling this is new positioning, not a hedge or a roll
- ⏰ January 2028 expiration — 21 months of time value; enough runway to see multiple earnings cycles, a potential CEO re-rating, and secular catalyst development
- 🎯 $62.50 strike — 23% out of the money from $50.67; the buyer needs a meaningful rally just to get in the money
- 📈 Breakeven at $69.32 ($62.50 strike + $6.82 premium) — that's a 37% move required to profit by expiration
- 🔥 Z-Score: 74.56 (EXTREMELY UNUSUAL) — this kind of block activity in PYPL options happens only a handful of times per year; a trade this size relative to recent average flow stands out dramatically
Real talk: Whoever bought these calls knows they need PayPal to do something it hasn't done in years — break out above prior resistance and sustain momentum. The 21-month timeframe is not an accident; it's calibrated to capture Enrique Lores's first full year in the CEO seat, multiple earnings reports, and the maturation of PayPal's three secular growth bets.
📈 Technical Setup / Chart Check-Up
YTD Performance
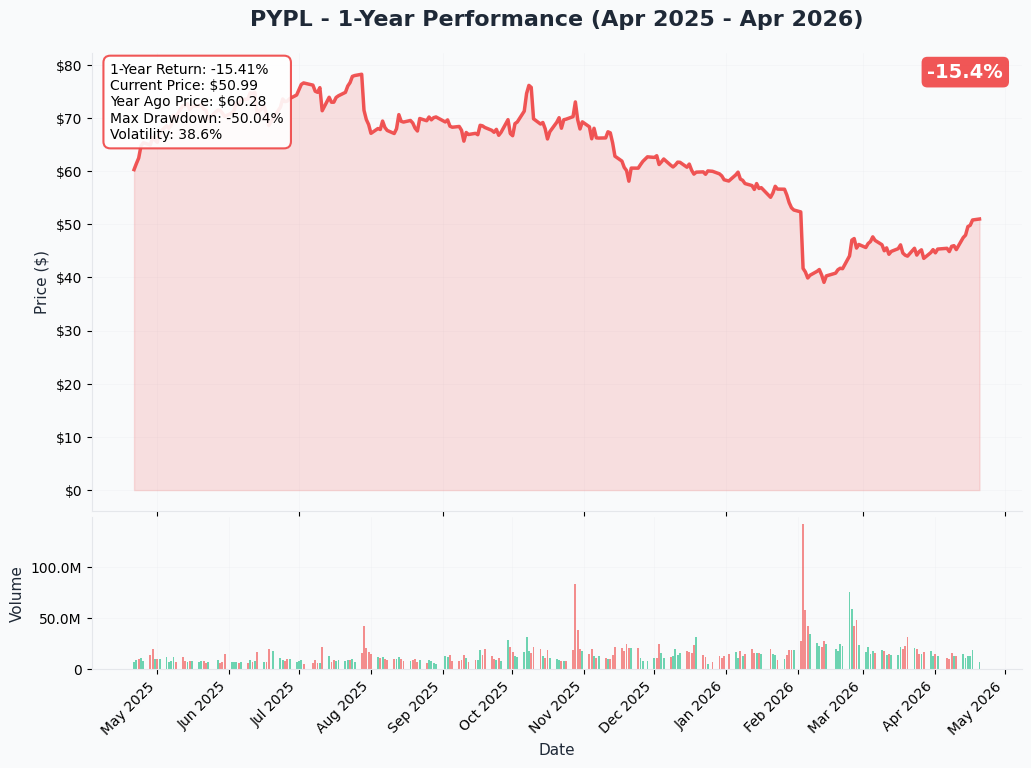
PYPL is down roughly 18% year-to-date from the ~$61-62 range it started 2026, currently hovering around $50.67. The stock has spent much of the year in a painful chop after the Q4 2025 earnings miss and simultaneous CEO replacement on February 3, 2026. The 52-week range of $38.46–$79.50 shows just how volatile this name has been — it's already recovered meaningfully off the lows, but it's still nowhere near the highs.
Key observations from the YTD chart:
- 📉 Sharp February selloff after the Q4 miss and Chriss ouster, flushing down toward the $38–40 range
- 🔄 Recovery and consolidation in the $48–52 zone as Lores took the reins in March
- 📊 $50 acting as a magnet — this lines up precisely with the strongest gamma support level identified below
Gamma-Based Support & Resistance
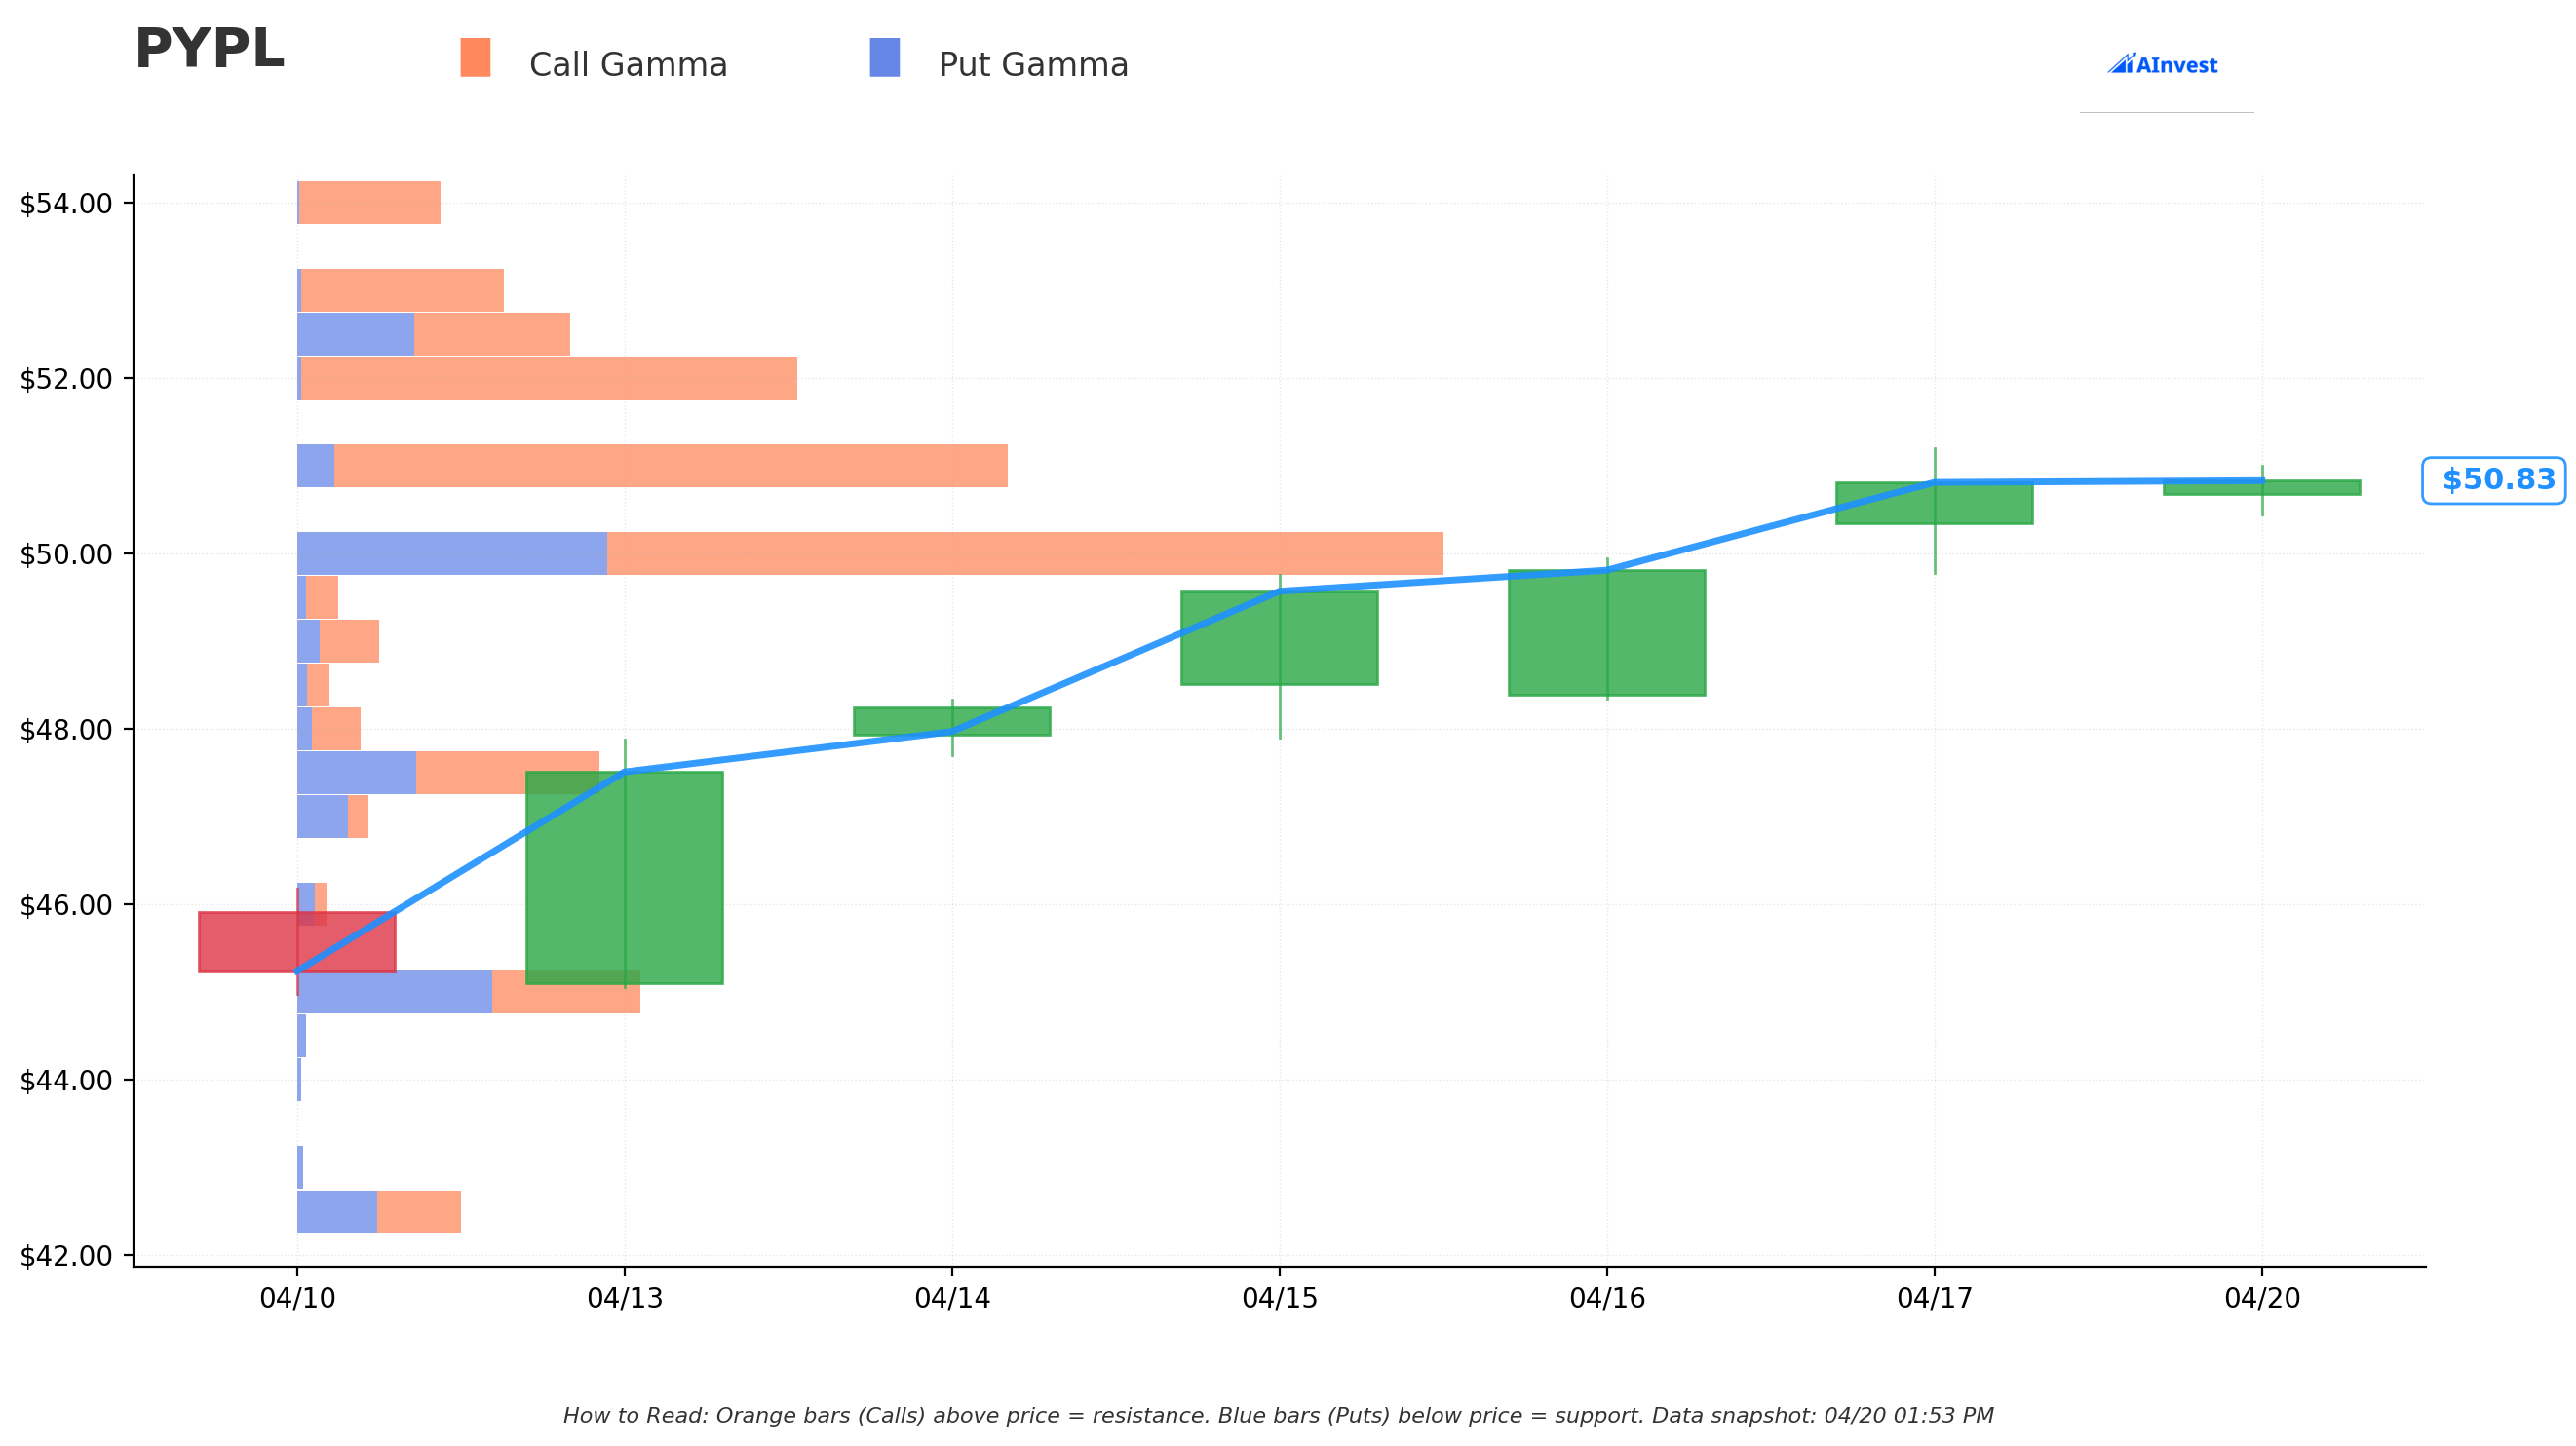
The gamma exposure map shows where market makers have the heaviest hedging activity — these are the price levels that act as real magnets and barriers:
🔵 Support Levels (Put Gamma Below Current Price):
- $50.00 — Strongest support in the chart with 28.4 total GEX. Call GEX dominates at 20.7 here, meaning dealers are long gamma and will buy dips aggressively. This is the key line in the sand — stock has been gravitating here for weeks.
- $47.50 — Secondary support at 7.5 total GEX (6.5% below current). A break here opens the door to the next zone.
- $45.00 — Deeper floor at 8.5 total GEX (11.4% below). Net GEX actually flips slightly bearish at this level, so it's a softer floor than $50.
🟠 Resistance Levels (Call Gamma Above Current Price):
- $51.00 — Immediate overhead resistance at 17.5 total GEX, just 0.4% above the current price. This is the first cap the bulls need to clear — and the fact that stock keeps running into it explains the recent chop.
- $52.00 — Next resistance at 12.3 total GEX (2.4% above). Clearing $52 would be a meaningful technical signal.
- $55.00 — Material call wall at 18.3 total GEX (8.3% above). This is where the story starts getting interesting for short-term traders.
- $60.00 — Extended resistance at 14.0 total GEX (18.1% above). Getting through $60 would represent a significant recapturing of lost ground and is where our LEAP buyer starts smiling.
Net GEX Bias: Bullish — Total call GEX (149.2) dwarfs put GEX (53.4), meaning the overall options market positioning is still tilted toward upside participation. Dealers are long gamma here, which tends to dampen volatility and create a "pinning" effect near big levels like $50–$51.
Implied Move Analysis
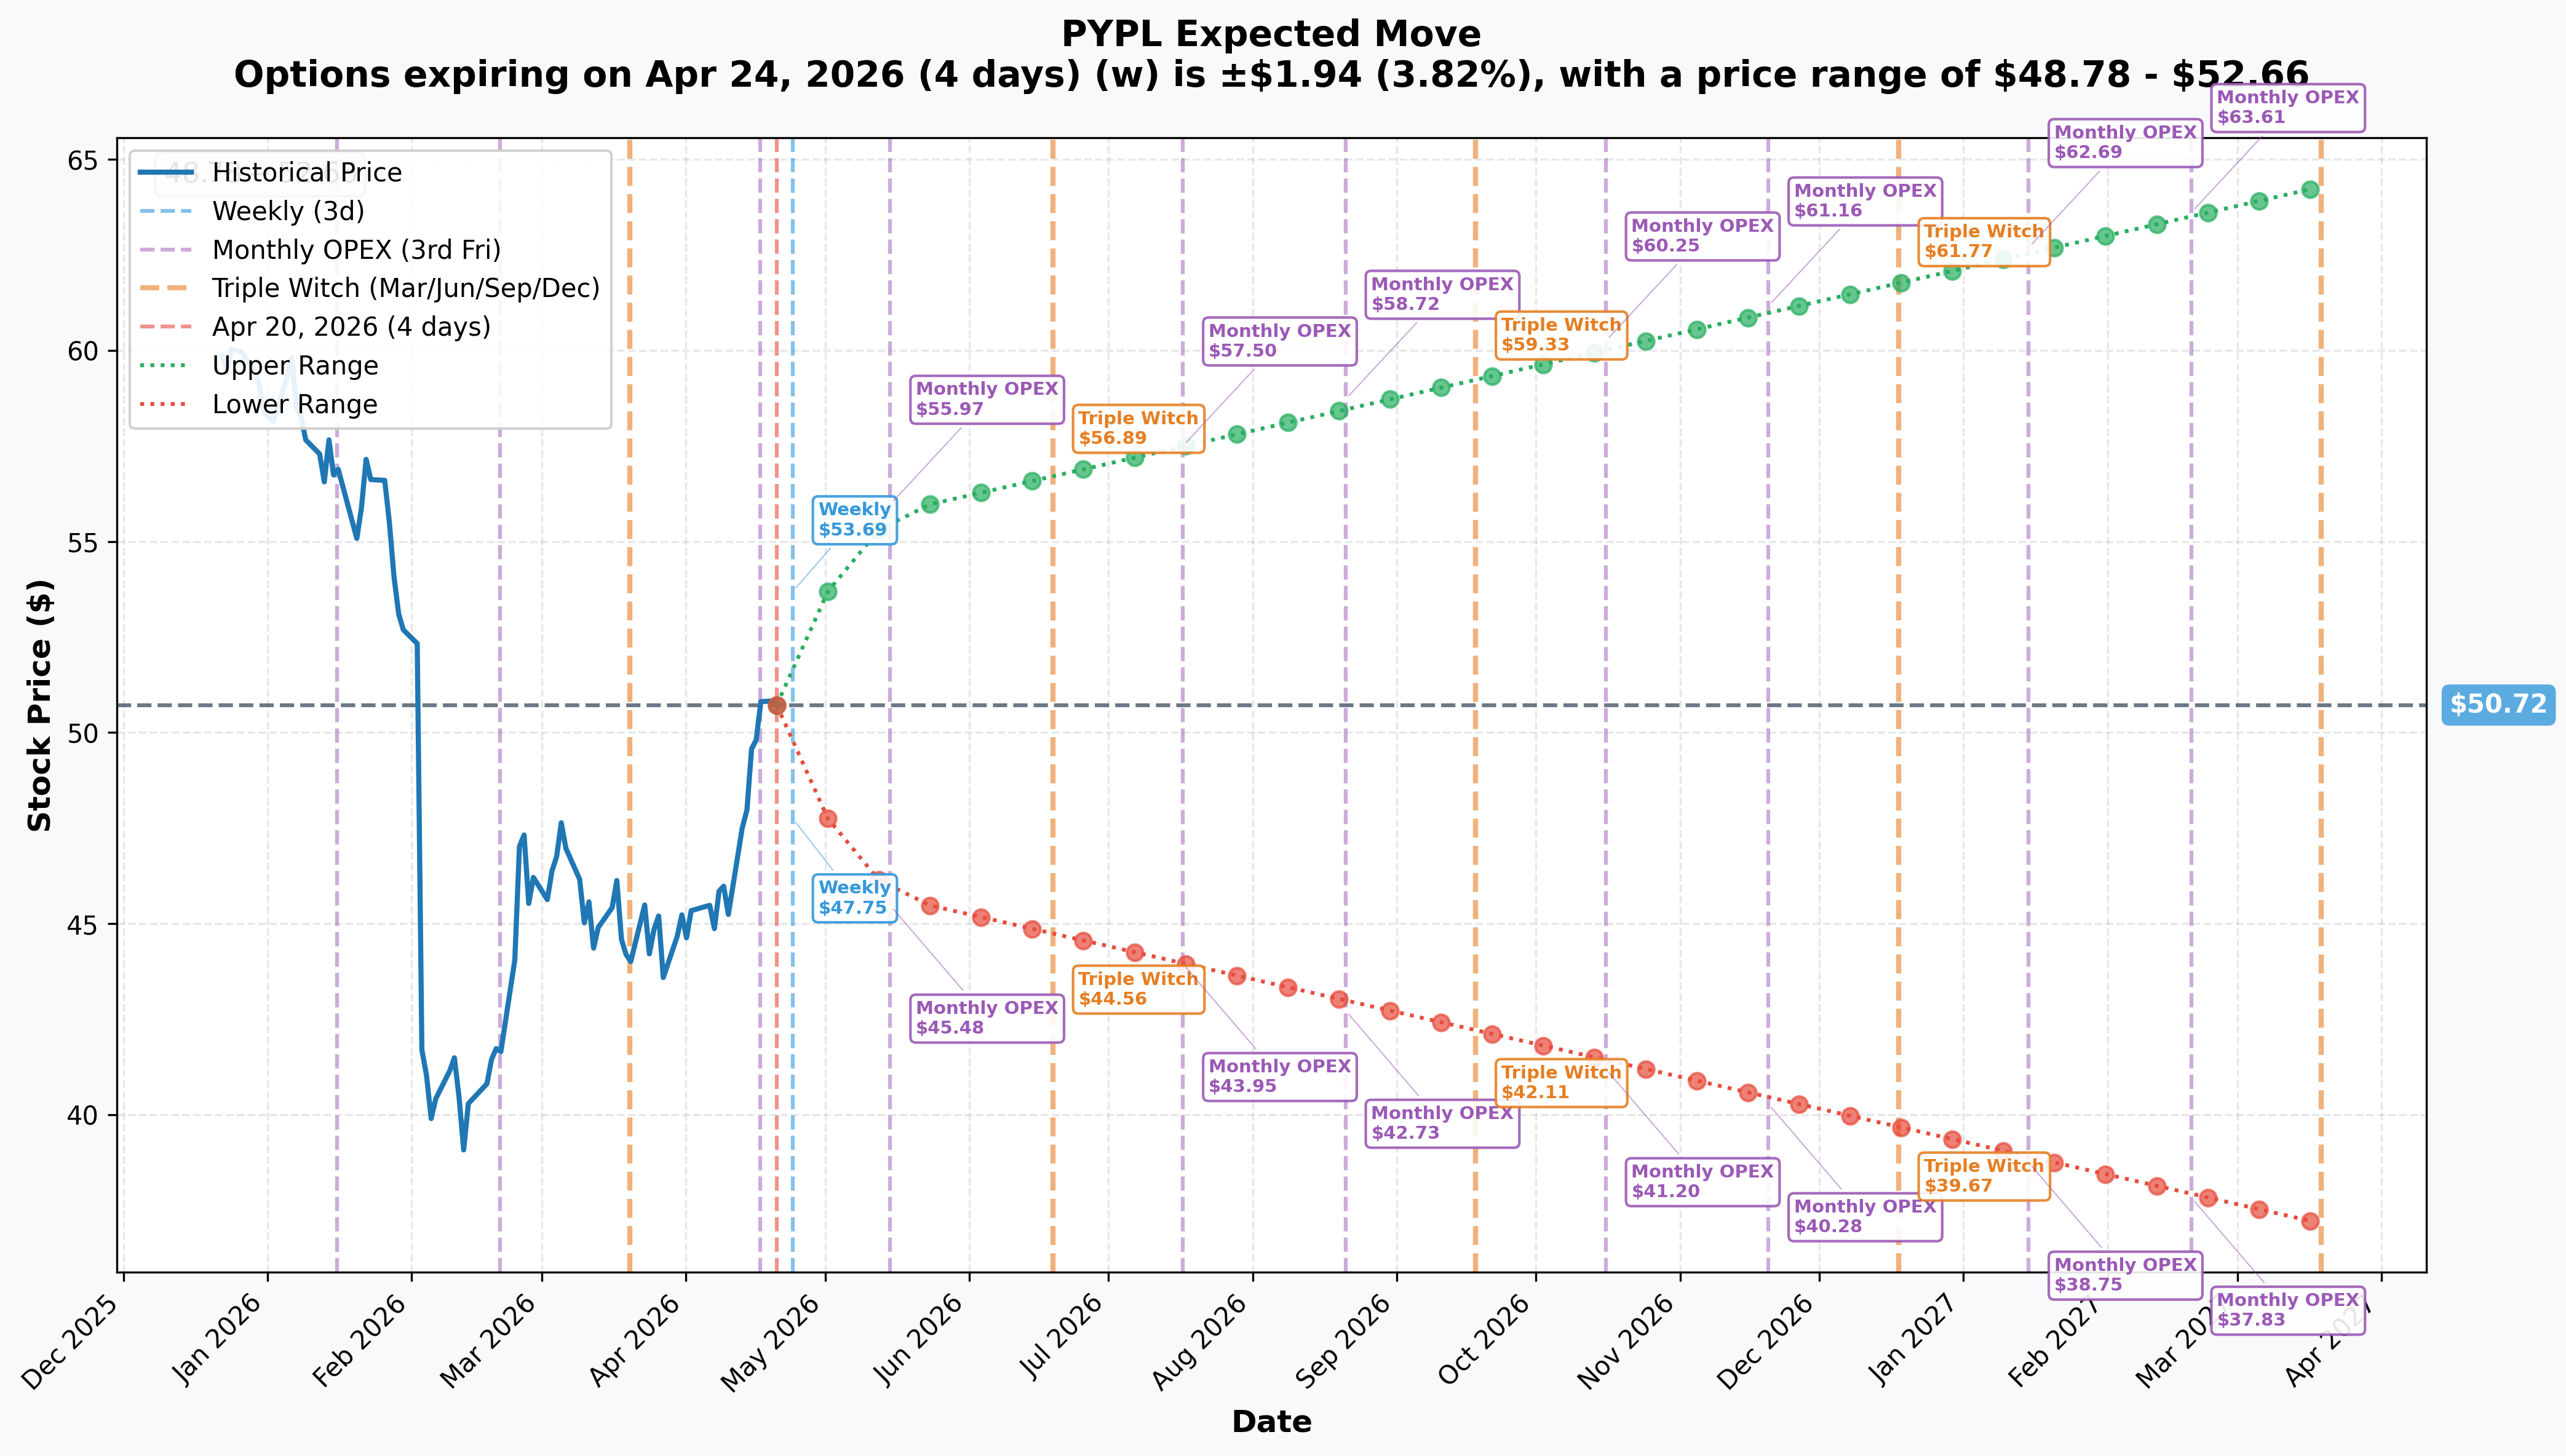
Here's what options markets are pricing for each upcoming expiration:
- 📅 Weekly (April 24 — 4 days): ±$1.94 (±3.8%) → Range: $48.78 – $52.66
- 📅 Monthly OPEX (May 15 — 25 days): ±$5.02 (±9.9%) → Range: $45.70 – $55.75 (includes May 5 Q1 earnings!)
- 📅 Triple Witch (June 19): Upper $56.89, Lower $44.56
- 📅 Monthly OPEX (July 17): Upper $57.50, Lower $43.95
- 📅 Monthly OPEX (October 16): Upper $60.25, Lower $41.20
- 📅 Monthly OPEX (November 20): Upper $61.16, Lower $40.28
- 📅 January OPEX 2027 (1-year out): Upper $62.69, Lower $38.75 ← right at the LEAP strike!
Translation for regular folks: The options market already prices a $62.69 upper range by January 2027 — which nearly touches our $62.50 LEAP strike. Our buyer gets 12 extra months beyond that (to January 2028) for their option to land in the money. The math says the market itself doesn't think this call is crazy — just ambitious.
🎪 Catalysts
🔥 Upcoming Catalysts (Next 12 Months)
Q1 2026 Earnings — Tuesday May 5, 2026 BMO (15 days away!) This is Enrique Lores's first earnings call as PayPal CEO — and the Street is watching like a hawk. Consensus expects EPS of $1.27 vs. $1.33 a year ago. The single most important data point: branded checkout growth. If it prints above 1% (the disastrous Q4 rate), the narrative shifts. If Lores provides forward guidance with conviction, the multiple could re-rate. This is a binary event with ±9.9% implied move priced in.
Agentic Commerce Scale-Up (2026 ongoing) PayPal and OpenAI's ChatGPT Instant Checkout partnership — announced October 28, 2025 — is rolling out across apparel, fashion, beauty, home improvement, and electronics in 2026. Perplexity Pro already enables in-chat PayPal/Venmo checkout. Google's Agent Payments Protocol and Anthropic/Claude (February 2026) further cement PayPal as the default payment rail for AI-driven commerce. If even one of these integrations scales meaningfully, it's a material incremental TPV driver that the market hasn't fully priced.
PYUSD Stablecoin + GENIUS Act (throughout 2026) PYUSD market cap hit ~$3.9-4B, up 680% YoY, and the GENIUS Act (S.1582) is providing regulatory clarity that positions PYUSD and USDC as the best-situated stablecoins. PayPal rolled PYUSD out across 70 international markets in early 2026. If stablecoin remittance volumes accelerate further, this becomes a real incremental revenue line.
PayPal Ads Manager (2026 ramp) Launched January 6, 2026, PayPal Ads leverages verified purchase data across 430M consumer accounts and tens of millions of merchants. Analysts estimate $150–500M incremental 2026 revenue. Ulta Beauty already reported a 20% lift in transaction spend from its first campaign. This is a high-margin business that hits directly to the bottom line.
Venmo $2B Revenue Journey Venmo grew 20% YoY in 2025. "Pay with Venmo" transaction volume up 50%, debit card TPV up 60%+. Management has set a $2B Venmo revenue target by 2027 — our LEAP expires January 2028, giving it nearly the full ride.
$6B 2026 Buyback Program PayPal is buying back ~$6B of its own stock this year, representing a 14.46% buyback yield — one of the most aggressive capital return programs in all of fintech. At a $45.8B market cap, they're retiring over 13% of shares per year. Every quarter that passes shrinks the float and provides a mechanical floor under the stock.
📋 Past Catalysts (Already Happened)
Q4 2025 Earnings Miss + CEO Ouster (February 3, 2026) PayPal reported Q4 2025 revenue of $8.68B vs. $8.79B consensus and non-GAAP EPS of $1.23 vs. $1.29 expected. The branded checkout growth collapse to 1% triggered the board to remove Alex Chriss same-day, parachuting in HP's Enrique Lores — a surprise move that rattled markets and set up the 18% YTD drawdown.
Fastlane & Agentic Commerce Launches (2025) PayPal deployed ChatGPT Enterprise across its 24,000+ employee workforce and formed the initial agentic commerce partnerships with OpenAI, Perplexity, and Google through late 2025 — all of which are now entering their commercialization phase in 2026.
🎲 Price Targets & Probabilities
Based on gamma levels, implied move data, and the LEAP structure:
📈 Bull Case — Lores Delivers (25% probability by expiration)
Target: $65–$70+ by January 2028
How we get there: Lores's first earnings call on May 5 shows branded checkout reaccelerating past 5%. Ads Manager exits 2026 with $300M+ run-rate revenue. PYUSD volumes drive incremental TPV. Agentic commerce with OpenAI/Perplexity generates measurable GMV in H2 2026. The P/E multiple re-rates from ~12x to 18-20x forward earnings — a natural compression as growth re-accelerates. The $62.50 LEAP call is well in the money, and the buyer's $6.82 premium has become multiples.
LEAP P&L at $68: Intrinsic value ~$5.50 + time premium → option worth ~$8-10. Profit on $1.7M outlay: meaningful. LEAP P&L at $75: Intrinsic value ~$12.50. Substantial return.
🎯 Base Case — Slow Grind (50% probability)
Target: $55–$62 by early-mid 2027, $62-68 by January 2028
Most likely scenario: Lores stops the branded checkout bleed and gets it back to 3-5% growth by Q3 2026. Ads Manager ramps slowly. PYUSD scales but CLARITY Act uncertainty keeps it from being a headline driver. The stock grinds from $50 toward the $55-60 gamma resistance zone over the next year. By January 2028, PYPL has recovered to $62–66. Our LEAP buyer is sitting on a modest profit or near breakeven — alive and playable.
The implied move data is instructive: the market already prices a $62.69 upper range by January 2027 — our strike. The LEAP buyer gets 12 extra months of time value on top of that.
📉 Bear Case — Turnaround Fails (25% probability)
Target: $38–$48 range through 2027
What could go wrong: Lores's Q1 2026 print shows branded checkout still stuck at 1-2%. The CLARITY Act bans stablecoin yield, gutting PYUSD's competitive advantage. Apple Pay, Shopify Payments, and Adyen continue compounding share gains. Morgan Stanley's $34 bear target gets validated. The $62.50 LEAP expires worthless. Maximum loss: the $1.7M premium ($6.82/contract × 2,500 contracts × 100).
💡 Trading Ideas
🛡️ Conservative: Wait for the May 5 Print
Strategy: Don't chase this LEAP today. Let Q1 2026 earnings clear first.
Why this works:
- 📅 May 5 BMO earnings is 15 days away and pricing ±9.9% implied move — a huge binary event
- 💸 If PYPL gaps down on another weak branded checkout print, you can buy a similar LEAP at a much lower cost basis
- ✅ If PYPL gaps up on Lores's guidance, you'll have confirmed the re-rating catalyst and can enter with conviction
- 📊 The $50 gamma support floor is strong — downside is bounded near-term even in a bad scenario
Action plan: Watch for branded checkout growth in Q1 call. If it's above 3%, consider buying the Jan 2028 $60 or $65 calls post-earnings IV crush. If it's still at 1%, step aside.
Risk level: Minimal (cash position) | Skill level: Beginner-friendly
⚖️ Balanced: Long Jan 2028 Call Spread (Copy the Direction, Define Your Risk)
Strategy: Buy the Jan 2028 $55 call, sell the Jan 2028 $70 call
Why this works:
- 💰 Buying the $55 call reduces your cost significantly vs. the $62.50 strike (closer to ATM = cheaper per delta)
- 🛡️ Selling the $70 call finances part of the premium — caps your upside at $70 but reduces outlay
- 📊 $55-$70 range captures the realistic bull case (23-38% rally) without paying for moonshots
- 🎯 Breakeven around $58-59 — a 15-17% rally, much more achievable than the 37% required for the flat call
- ⏰ 21 months of time for PayPal to execute across multiple earnings cycles
Estimated cost: Roughly $3-4 net debit for the spread vs. $6.82 for the flat call. Max profit ~$11-12 per spread if PYPL hits $70+.
Position sizing: Risk only 2-4% of portfolio on a speculative turnaround bet like this.
Risk level: Moderate (defined max loss = net debit paid) | Skill level: Intermediate
🚀 Aggressive: Mirror the Whale (Long Jan 2028 $62.50 Call)
Strategy: Buy the Jan 2028 $62.50 call — same structure as the $1.7M whale trade
Why this could work:
- 🐋 Someone put $1.7M behind this specific strike and expiration — that's not a rookie move
- ⏰ 21 months gives Lores 6+ earnings calls to fix branded checkout, scale PYUSD, and ramp Ads Manager
- 📈 Implied move data prices the $62.69 upper range by January 2027 — this strike is within the 1-year range already
- 💸 $14% buyback yield shrinks the float every quarter, providing mechanical EPS support
- 🎰 Options are relatively cheap at ~12-13% IV for a LEAP this far out — you're not overpaying for time
Why this could blow up:
- ❌ 37% rally required just to break even — that's a lot to ask from a stock in a managed decline
- ❌ Morgan Stanley's $34 bear case exists for a reason — branded checkout at 1% is a structural concern
- ❌ If you pay $6.82 and PYPL is at $58 in January 2028, you lose everything
- ⚠️ LEAP theta decay accelerates as you approach expiration — don't wait too long to reassess
Breakeven analysis:
- 📈 Breakeven: $69.32 by January 21, 2028 (37% rally from $50.67)
- 🎯 Strike: $62.50 (needs 23% rally to be in the money)
- 💀 Max loss: $6.82 per contract (100% of premium)
Critical warning: Only attempt this if you can afford to lose 100% of premium. Size appropriately — 1-2% of portfolio maximum for this type of speculative LEAP.
Risk level: HIGH (100% loss possible) | Skill level: Experienced options traders only
⚠️ Risk Factors
Don't get blindsided by these potential landmines:
-
⏰ Binary Q1 earnings in 15 days: May 5 BMO is the first major test for Lores. If branded checkout comes in at 1% again, the stock could flush toward $44-45 (monthly implied move lower bound). LEAP holders would see their $6.82 option drop meaningfully in value even though expiration is 21 months away — time value won't save you from a large delta move.
-
📉 Branded checkout structural decline: Apple Pay, Shop Pay, and Adyen are compounding gains. PayPal's SMB TPV actually declined in dollar terms from 2022 to 2024. If the underlying checkout business continues to lose share, no CEO can fix it with secular tailwinds alone.
-
💸 CLARITY Act stablecoin yield ban: The January 2026 draft CLARITY Act proposes banning yield on payment stablecoins. If passed, PYUSD's 4% merchant reward and 3.7% consumer APY disappear — gutting the primary competitive advantage of PYUSD versus alternatives.
-
📊 2026 guidance is not bullish: Management itself guided transaction margin dollars to be roughly flat for full year 2026, with EPS down low single digits to slightly positive. This is not a high-growth setup — it's a "show me" story where the LEAP buyer is betting on an eventual multiple re-rating that management hasn't promised.
-
🐻 Morgan Stanley bear case at $34: The most bearish major analyst has a price target of $34 — 33% below current levels. If macro deteriorates or branded checkout continues eroding, the stock could revisit the $38-40 area, making the LEAP worthless.
-
🎯 Execution risk under new CEO: Lores spent his career at HP hardware — he has no direct fintech or payments operating experience. The board's own public rebuke of Chriss ("pace of change not in line with expectations") signals they want speed. If Lores also struggles to move the needle, the stock faces a re-rating to a lower multiple.
-
🔄 Takeover optionality — a double-edged sword: PayPal has been speculated as an M&A target at current valuations. A low-premium acquisition would cap upside for LEAP holders — you could be right on the business but still see the option expire worthless if a deal gets done at $60 instead of $75.
🎯 The Bottom Line
Here's the deal: A sophisticated buyer just committed $1.7 million to a 21-month, 37%-out-of-the-money call on PayPal. This is not a hedge — the Vol/OI of 4.13x makes clear this is fresh bullish positioning. It is a long-duration bet on a specific thesis: that Enrique Lores can do for PayPal what he couldn't fully do for HP — rationalize costs, drive growth in adjacent businesses, and eventually re-rate the multiple.
The structure is deliberate. January 2028 gives Lores roughly 7 quarters to deliver results before this option expires. It encompasses:
- 📅 May 5, 2026 — Q1 2026 earnings, first Lores print
- 📅 Q2-Q4 2026 — Ads Manager ramp, PYUSD scaling, agentic commerce GMV
- 📅 2027 — Venmo $2B revenue target approach, Fastlane biometric expansion
- 📅 January 21, 2028 — LEAP expiration
The gamma data says $50 is the fortress support and $51 is the immediate ceiling. Clearing $51 — just $0.33 above current price — would be the first signal that the base is forming. The implied move data says the options market itself prices a $62.69 upper range by January 2027, nearly touching our strike a full year before expiration. The buyer has time on their side.
If you own PYPL stock:
- ✅ Hold through May 5 earnings — the risk/reward for stock holders is reasonable with $50 gamma support beneath you
- 📊 Watch for branded checkout growth acceleration above 3% as the key signal
- 🎯 If PYPL breaks $55 on strong Lores guidance, the re-rating narrative has legs
- ⚠️ Set a mental stop below $47.50 (next gamma support) — losing that level opens the door to $44-45
If you're watching from the sidelines:
- ⏰ Mark your calendar for May 5 BMO — that's the decision point. Do not enter any LEAP before that print
- 🎯 Post-earnings, look for: branded checkout above 3%, Ads Manager early revenue, Venmo debit card metrics
- 📈 A clean beat with optimistic Lores guidance could move the stock to $54-55 quickly — and that's where LEAPs become attractive on the dip
If you're bearish:
- 🎯 $51 is your first signal that bulls are losing control — break above that with conviction = cover shorts
- 📉 Below $47.50 puts $45 support in play; below $45 and the 52-week low ($38.46) becomes the target
- ⚠️ Do not fight the buyback — $6B per year at this market cap is a floor that keeps getting stronger as shares get retired
Final verdict: The $1.7M LEAP trade is a sophisticated, patient bet on a company that has all the raw ingredients for a turnaround — massive consumer network, powerful FCF engine, emerging stablecoin and agentic commerce franchises — but has consistently failed on execution at the branded checkout level. The trade makes money only if Lores is different. The 21-month runway says: let's find out. That's an intellectually honest bet. Just make sure you size it appropriately, because a lot needs to go right to reach $69.32.
Mark your calendar:
- 📅 May 5, 2026 BMO — Q1 2026 earnings under Lores (THE catalyst)
- 📅 May 15, 2026 — Monthly OPEX (±9.9% implied move window)
- 📅 June 19, 2026 — Triple Witch quarterly expiration
- 📅 October 16, 2026 — Implied move upper bound $60.25 (approaching the strike)
- 📅 January 15, 2027 — Implied upper range $62.69 (strike territory, one year early)
- 📅 January 21, 2028 — LEAP expiration
Disclaimer: Options trading involves substantial risk of loss and is not suitable for all investors. This analysis is for educational purposes only and does not constitute financial advice. Past unusual options activity does not guarantee future performance. A Z-score of 74.56 reflects the relative unusualness of this trade compared to recent PYPL options history — it describes the size of the bet, not its probability of success. The breakeven of $69.32 requires a 37% rally from current prices — a significant hurdle that may not be achieved. LEAPs can expire worthless, resulting in a 100% loss of premium. Always do your own research and consider consulting a licensed financial advisor before trading. Position sizing is critical: never risk more than you can afford to lose on speculative long-dated options.
About PayPal Holdings: PayPal operates one of the world's largest open digital payments platforms with 439 million active accounts, $1.8 trillion in annual Total Payment Volume, and a market cap of approximately $45.8 billion. The company processes transactions across branded checkout (PayPal button), unbranded PSP (Braintree), and consumer P2P/commerce (Venmo), with emerging revenue lines in stablecoins (PYUSD), digital advertising (Ads Manager), and agentic commerce.