🐻 CDNS $38M Put Spread — Big Money Positioning Ahead of April Earnings! 📅
📅 March 24, 2026 | 🔥 Unusual Activity Detected
🎯 The Quick Take
Someone just structured a $38M put spread in Cadence Design Systems this morning at 10:01:15, sweeping across $265 and $290 strikes in a single coordinated move. With CDNS down -7.9% YTD and sitting roughly 22% off its 52-week high of $376.45, this is a sophisticated player making a defined-risk bet just 34 days before the critical Q1 2026 earnings on April 27. Translation: An institutional trader just locked in a large credit spread, betting CDNS holds above $290 — or is hedging a sizable long position into what could be a volatile earnings report.
📊 Company Overview
Cadence Design Systems (CDNS) is the indispensable software backbone of the global chip design industry:
- Market Cap: ~$80.7B
- Sector: Services — Prepackaged Software (EDA)
- Current Price: ~$285.97 (YTD: -7.9%)
- Primary Business: Electronic design automation (EDA) software, semiconductor IP, and system design & analysis tools used by virtually every major chip company on the planet — from NVIDIA to Qualcomm to Micron
Cadence operates as part of a near-duopoly alongside Synopsys in a market where customers almost never leave. With a record $7.8B backlog entering 2026, the recently completed $2.7B Hexagon D&E acquisition, and the just-launched ChipStack AI Super Agent — CDNS is a company where the fundamentals are genuinely strong, but the valuation at ~72x P/E leaves very little margin for error.
💰 The Option Flow Breakdown
📊 What Just Happened — The Tape (March 24, 2026 @ 10:01:15)
| Time | Symbol | Side | Buy/Sell | Call/Put | Expiration | Premium | Strike | Volume | OI | Size | Spot | Option Price | Option Symbol |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 10:01:15 | CDNS | MID | BUY | PUT | 2026-06-18 | $17M | 265 | 10K | 0 | 9,996 | $278.84 | $17.41 | CDNS20260618P265 |
| 10:01:15 | CDNS | MID | SELL | PUT | 2026-06-18 | $14M | 290 | 7.5K | 1.3K | 4,998 | $278.84 | $28.96 | CDNS20260618P290 |
| 10:01:15 | CDNS | MID | SELL | PUT | 2026-06-18 | $7.2M | 290 | 2.5K | 1.3K | 2,499 | $278.84 | $28.97 | CDNS20260618P290 |
Total premium across all legs: ~$38.2M
🤓 What This Actually Means
Let me break this down in plain English. Three legs, all hitting at the exact same timestamp — this is not random retail trading. It's one coordinated institutional spread.
Here's the structure:
- 🔵 Buy 10,000 contracts of the $265 put (paid $17M) — this is the protection leg, buying the right to sell CDNS at $265. Zero open interest before this trade means it was freshly opened today.
- 🟠 Sell 10,000 contracts of the $290 put (collected $21.2M, split across two fills) — these are deep in-the-money puts at $290 when spot is $278.84. Selling ITM puts at this level is unusual.
Net result: A ~$4.2M credit collected.
The $290 put sells are flagged with a Z-score of 46.39 at 5.77x average daily volume — the kind of activity that shows up maybe a few times a year for this ticker at this size. The $265 buys had zero prior open interest, so this is new positioning, not a roll.
Strategy: Bull Put Spread (Credit Spread)
This is a textbook Bull Put Spread — selling the higher-strike $290 put and buying the lower-strike $265 put at the same June 18 expiration. The structure collects a net credit upfront and profits if CDNS remains above the short strike at expiration.
- Net credit collected: ~$4.2M ($21.2M premium received on $290 puts minus $17M paid on $265 puts)
- Maximum profit: $4.2M — achieved if CDNS closes above $290 on June 18
- Maximum loss: ~$20.8M — if CDNS closes below $265 on June 18 ($25 spread width × 10,000 contracts × 100 = $25M risk, net of $4.2M credit)
- Breakeven: ~$285.80 (short strike $290 minus $4.20 net credit per share)
The $290/$265 strikes are not arbitrary — they align precisely with the two most prominent put-gamma clusters flanking current price. The short $290 put is at the nearest call-dominated resistance level; the long $265 put sits at the third-strongest put-gamma support. This is a conviction trade that CDNS recovers above $290 or at minimum holds near current levels through June expiry.
This is an experienced institutional player making a structured, defined-risk bet — not a panic trade.
📈 Technical Setup / Chart Check-Up
YTD Performance
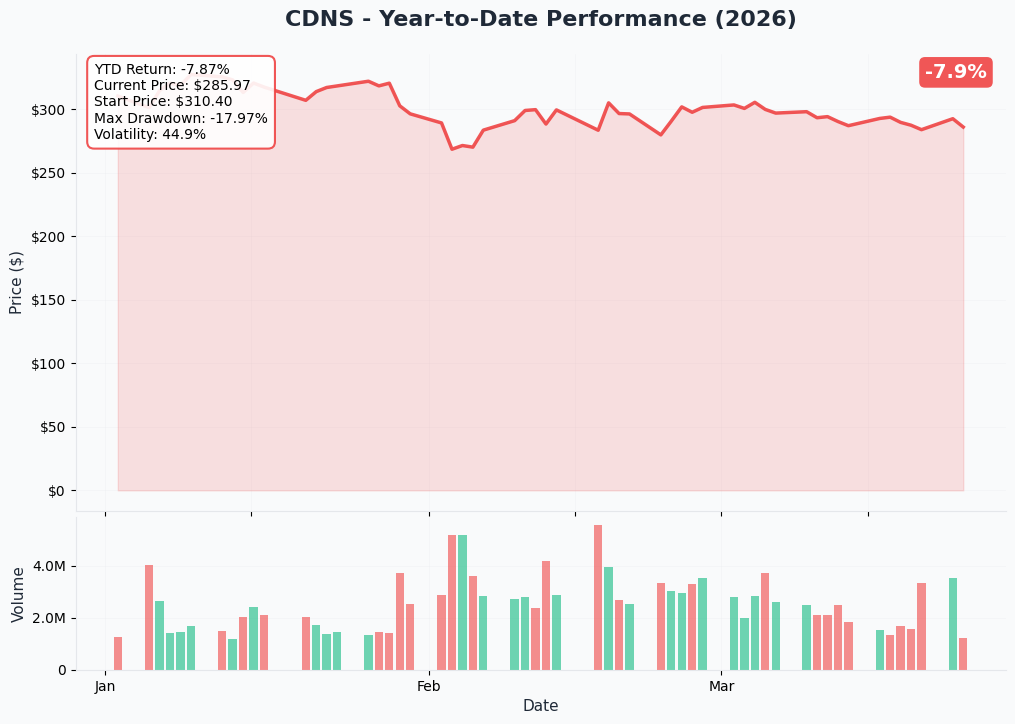
CDNS has struggled in 2026, down -7.9% YTD from its January 1 start near $310.50, and sitting roughly 22% below its 52-week high of $376.45. The stock made a sharp V-shaped recovery attempt from its post-Hexagon announcement dip but has been unable to reclaim its late-2025 highs. The current price around $285.97 puts it right in the contested zone between the $270 and $290 gamma levels — a crucial area for options traders.
Key observations:
- 📉 Valuation de-rating in progress: The pullback from $376 reflects P/E compression broadly, not company-specific bad news
- 🔑 Support test: The $275-$280 range has been a battleground — the spot price of $278.84 at time of the trade was near recent lows
- 📊 Still above 52-week low: $221.56 is the true floor — significant cushion, but multiple compression risk remains real
- 🎯 Earnings inflection point: April 27 Q1 earnings could reset the narrative either way
🔵🟠 Gamma-Based Support & Resistance
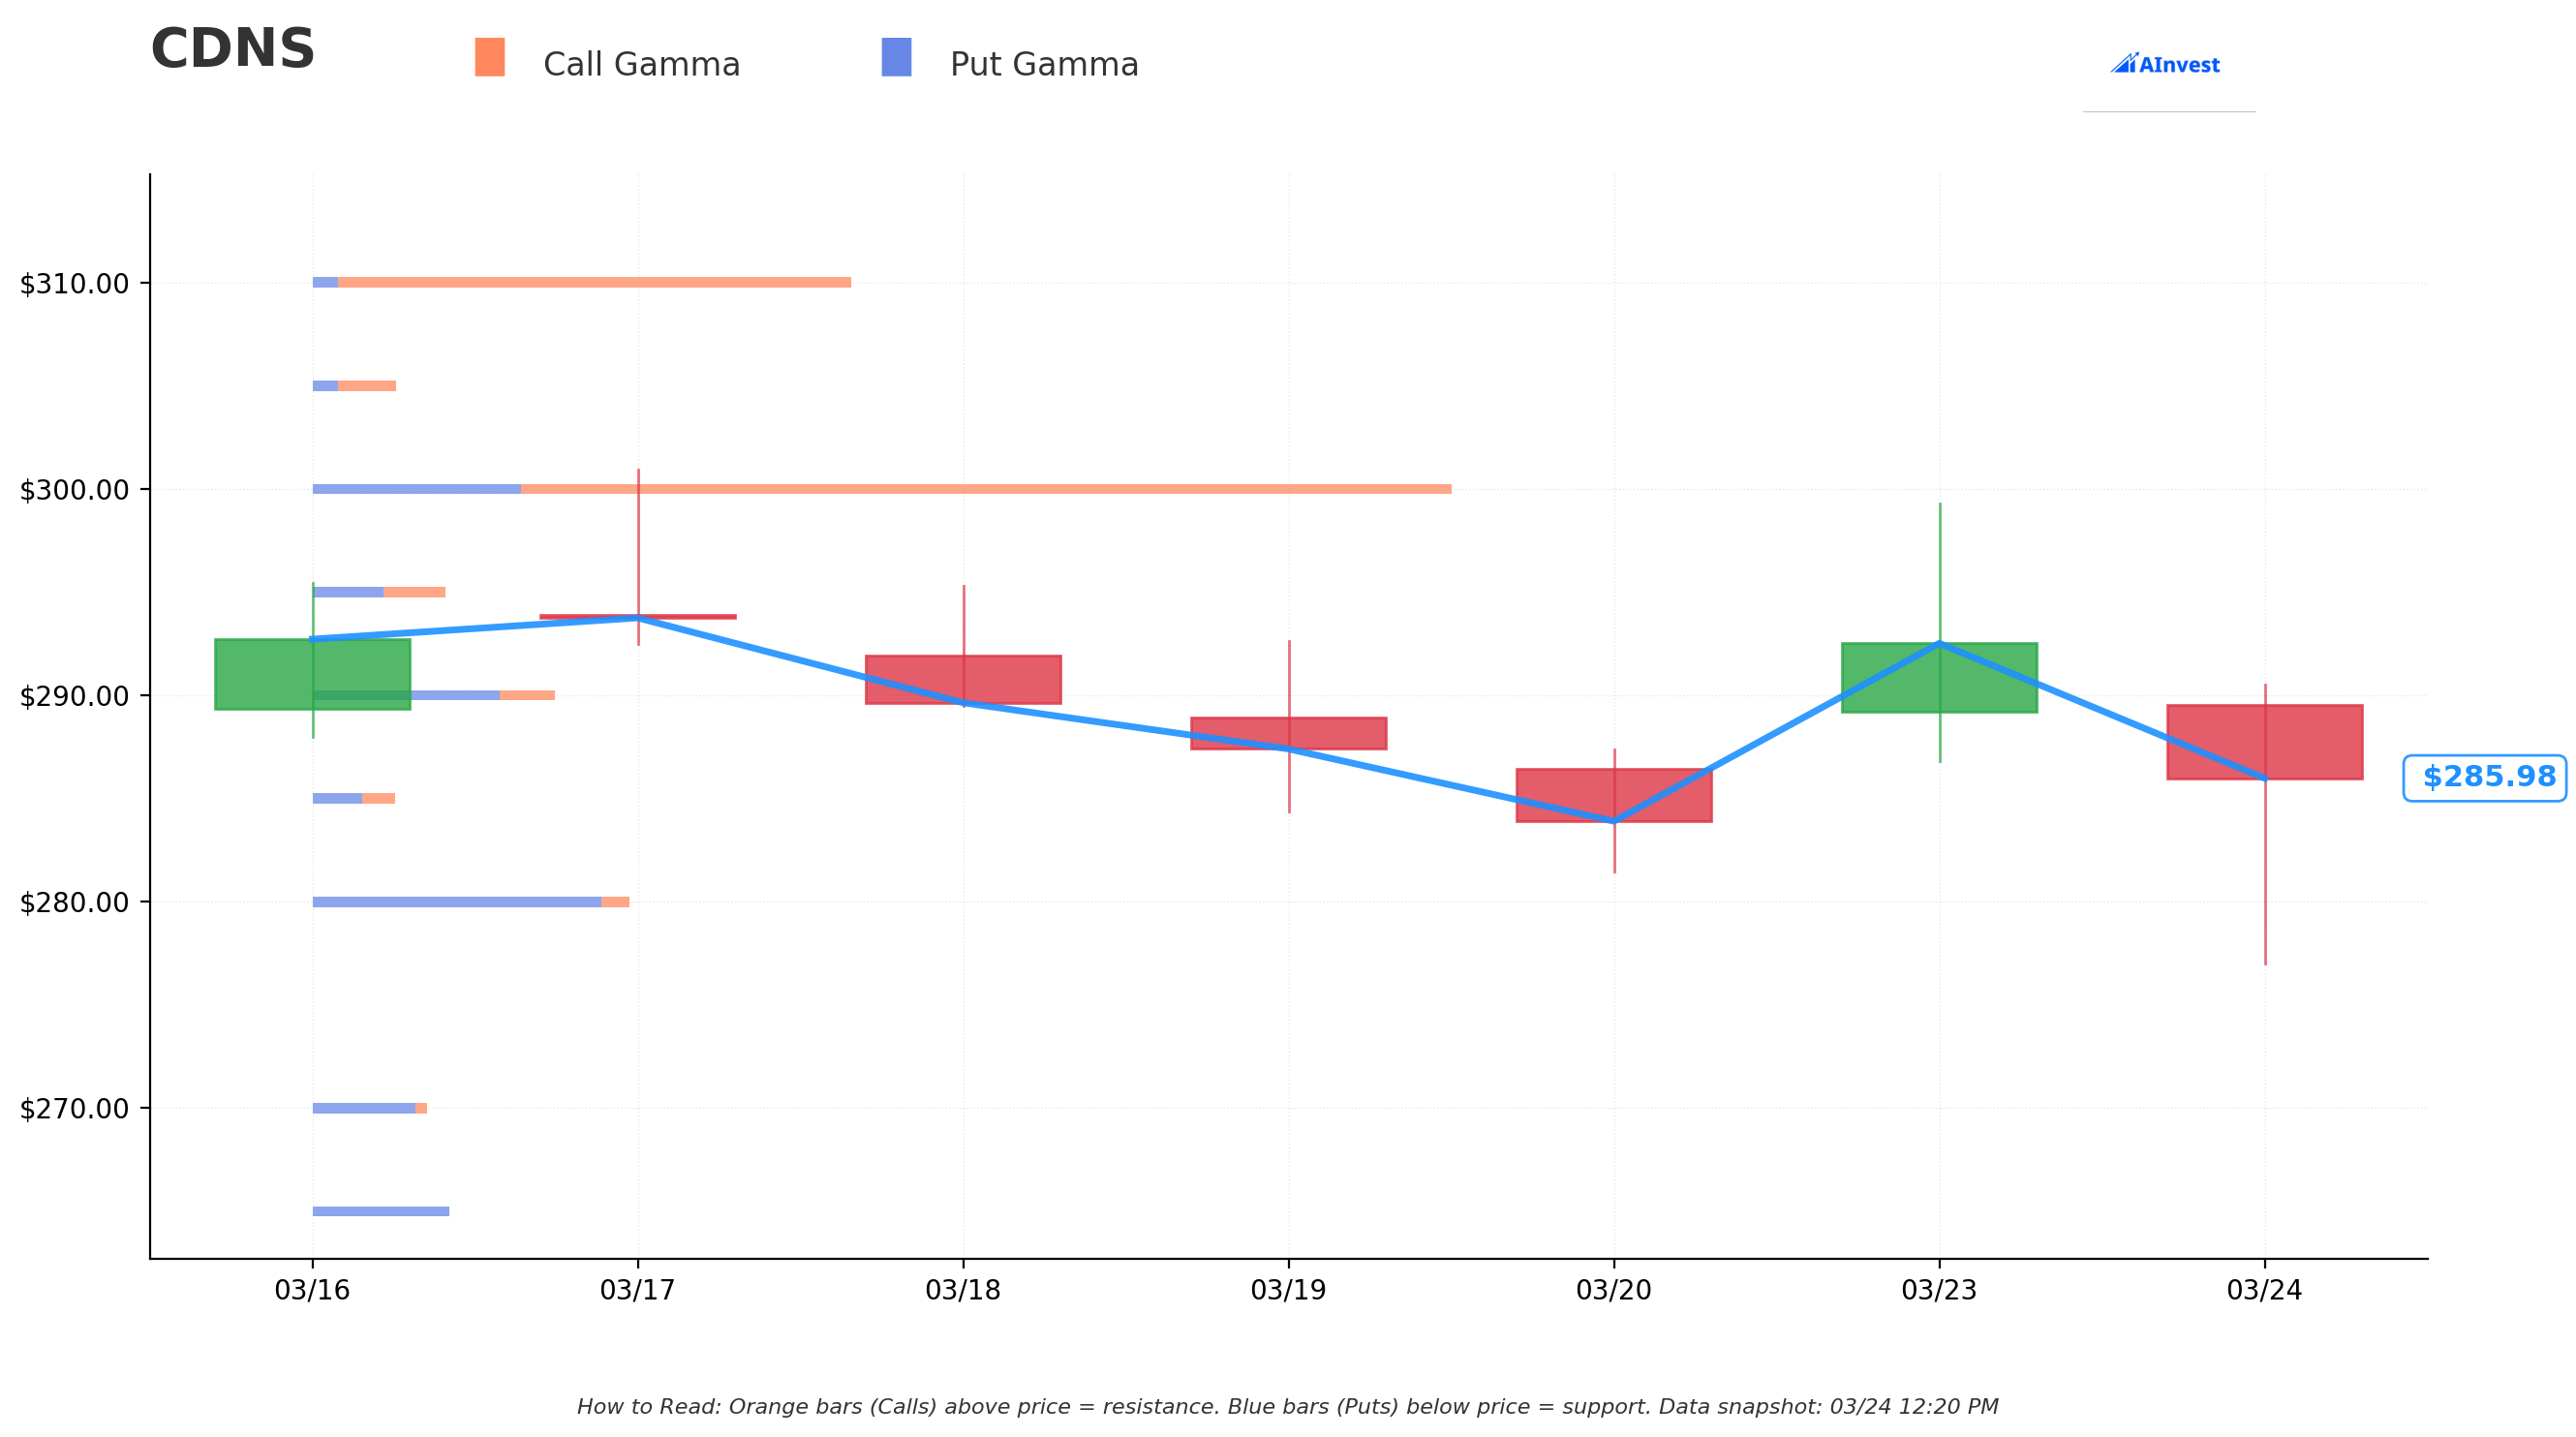
Current Price: $285.99
The gamma exposure map gives us a clear picture of where market makers are most concentrated — and where price tends to gravitate (or bounce hard).
🔵 Support Levels (Put Gamma Below Price):
- $280 — Nearest support, 0.51B total gamma | ~2.1% below current price. This is the most active put gamma cluster nearby. If CDNS holds $280, gamma pinning should slow the decline.
- $270 — Secondary support, 0.18B total gamma | ~5.6% below. A meaningful step down from $280.
- $265 — Third support, 0.23B total gamma | ~7.3% below. Notably, this is exactly where the institutional buyer struck their long puts today. Not a coincidence — they're targeting the level where put gamma is concentrated and a break lower could accelerate.
- $230 — Deep floor, 0.17B gamma | ~19.6% below. Worst-case structural support.
🟠 Resistance Levels (Call Gamma Above Price):
- $290 — Nearest resistance, 0.39B total gamma | ~1.4% above current price. This is exactly the short put strike in today's trade. At the strongest nearby resistance, the trader sold puts here betting the stock stays below $290 — or expecting a breakout above it by June.
- $295 — Secondary resistance, 0.21B gamma | ~3.2% above.
- $300 — Major resistance ceiling, 1.83B total gamma | ~4.9% above. This is by far the strongest gamma level on the board — dominated by call gamma (1.50B vs 0.34B put gamma). Price reaching $300 will face enormous selling pressure from market makers.
- $310 — Extended resistance, 0.87B gamma | ~8.4% above.
- $320 — Further resistance, 0.98B gamma | ~11.9% above.
What this means for traders:
CDNS is sitting in a $280-$290 compression zone — squeezed between the strongest nearby support at $280 and resistance at $290. The $300 level with 1.83B gamma is the BIG wall — a rally there will be fought hard. The gamma data explains why the institutional trader picked exactly $290 and $265 as their strikes: those are the two most prominent put-concentrated levels on either side of current price.
Net GEX Bias: Bullish (5.09B call gamma vs 3.11B put gamma overall) — the broader book is tilted bullish, even as the short-term setup looks constrained.
📐 Implied Move Analysis
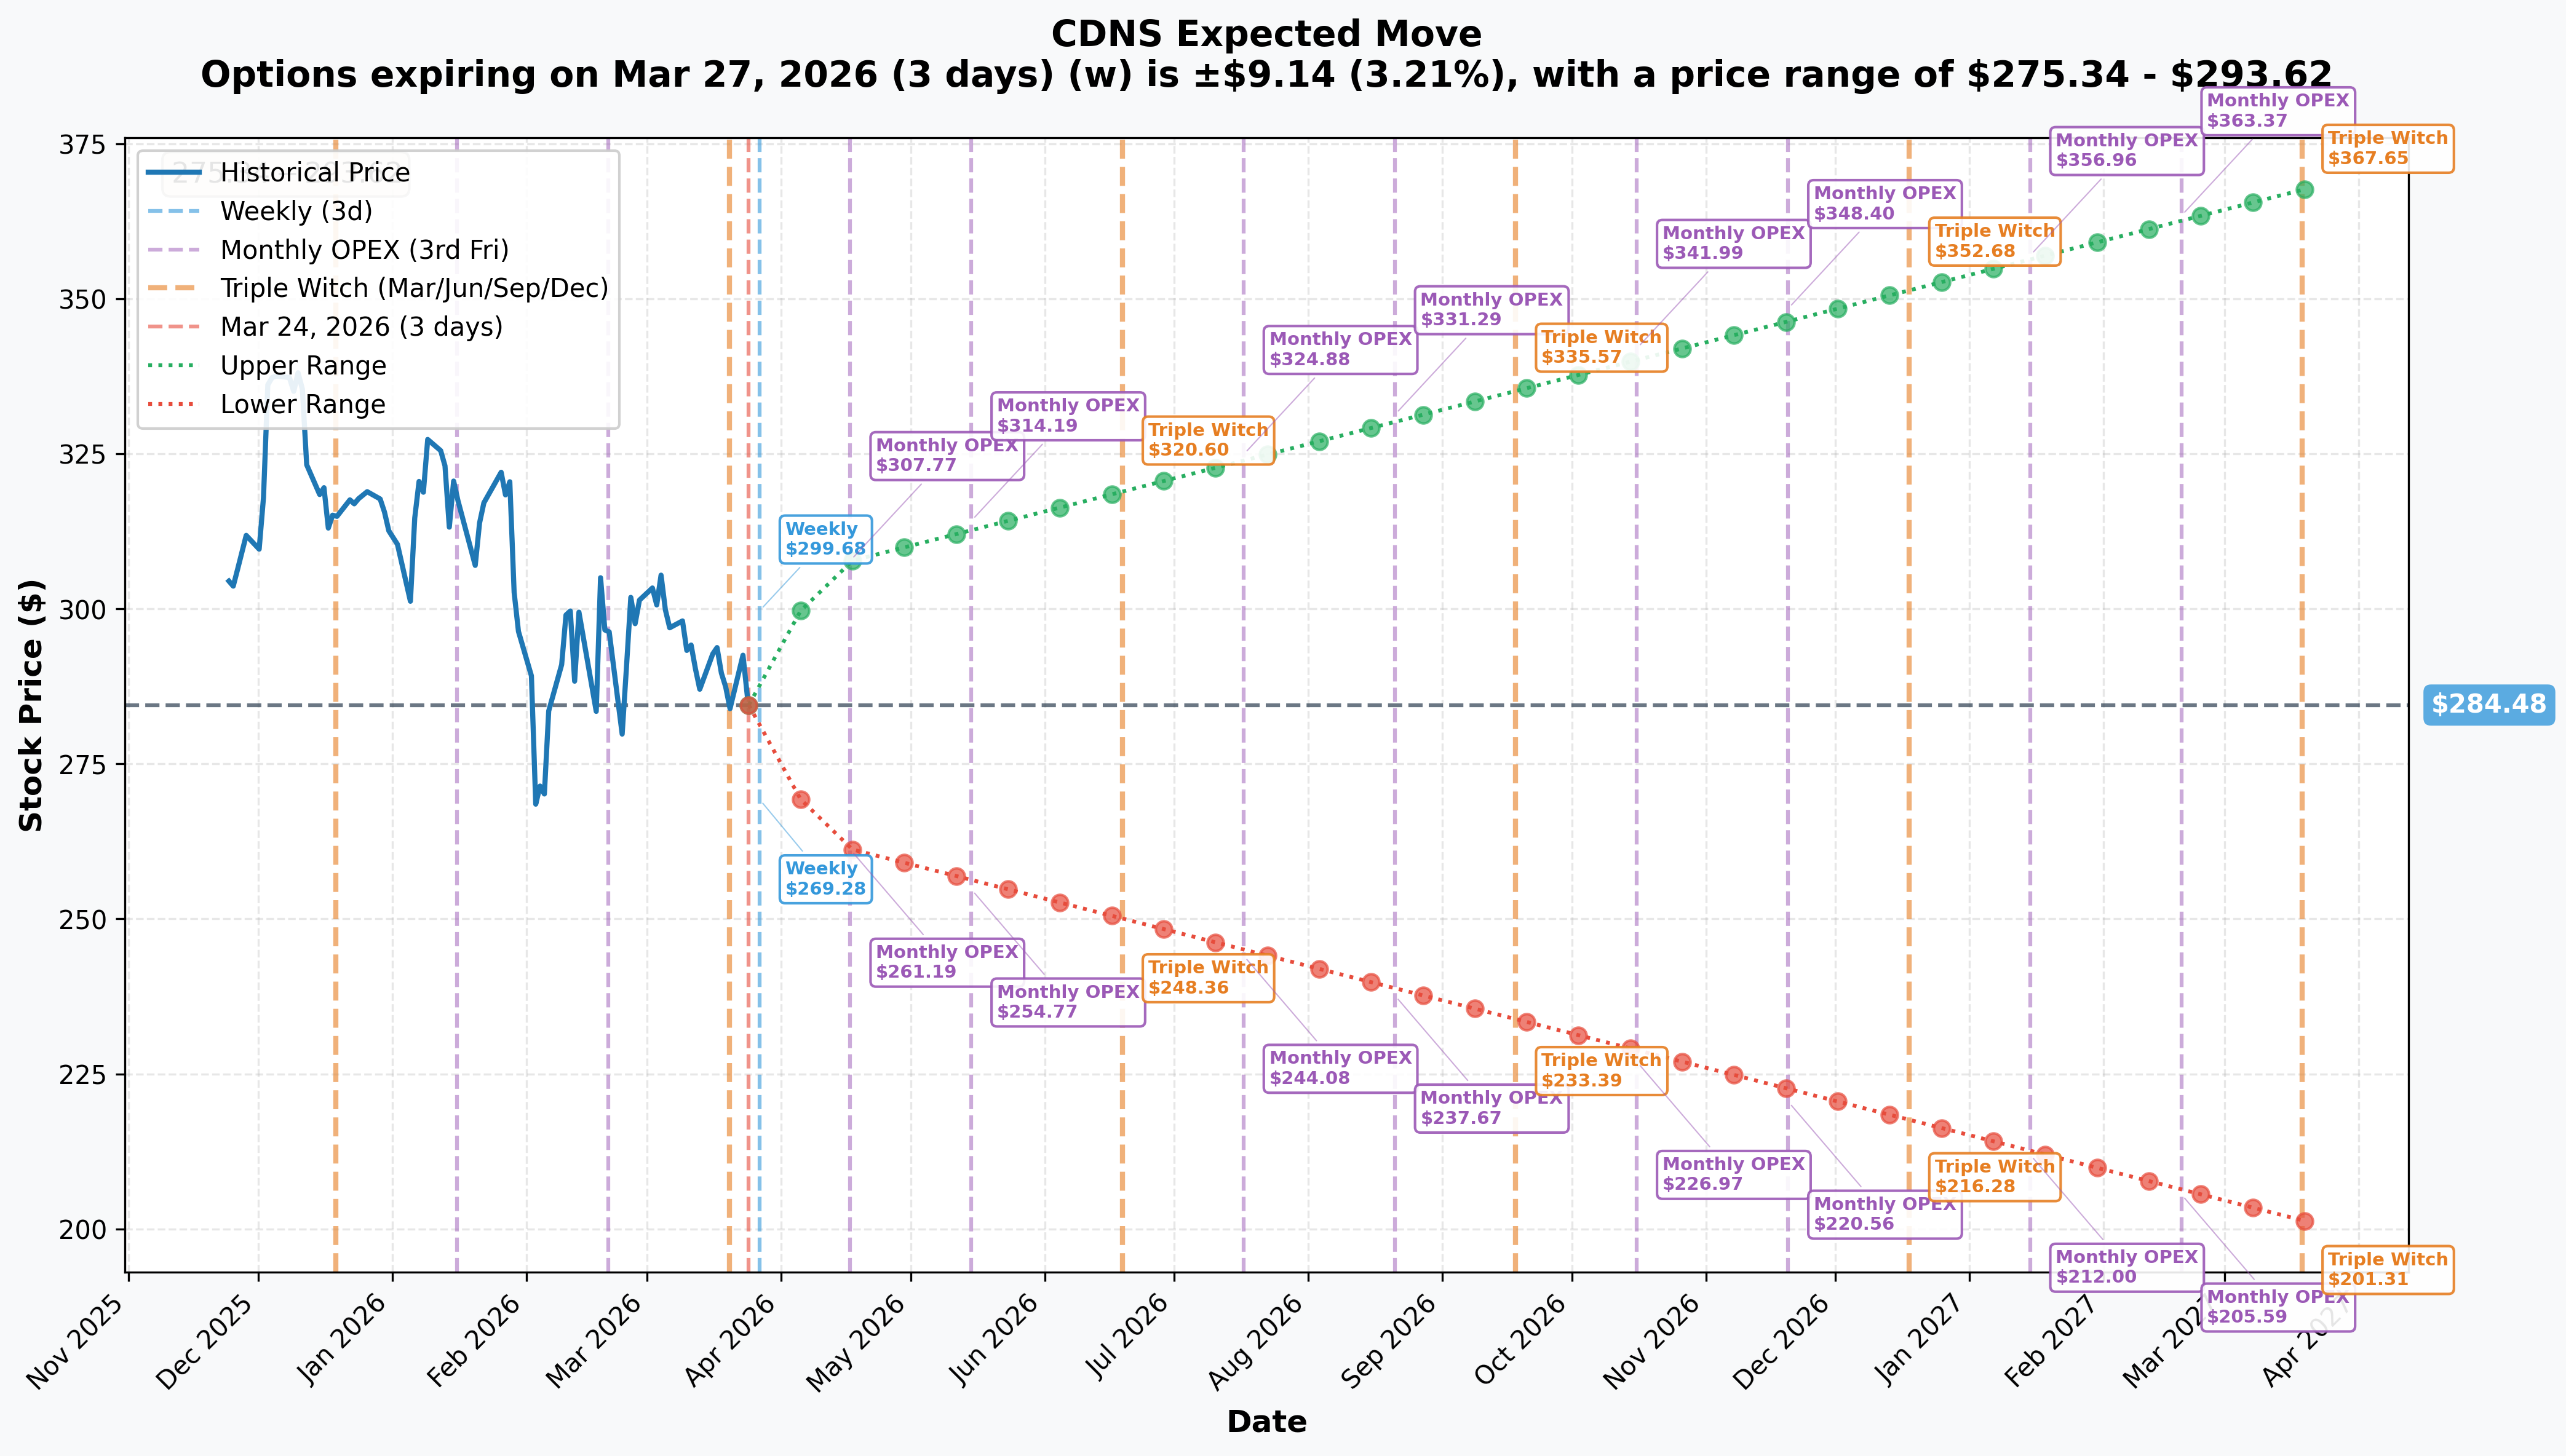
Options market pricing across key upcoming expirations:
- 📅 Weekly (March 27 — 3 days): ±$9.14 (±3.21%) → Range: $275.34 - $293.62
- 📅 Monthly OPEX (April 17 — 24 days): ±$23.29 (±8.19%) → Range: $261.19 - $307.77
- 📅 June Triple Witch (June 19 — this trade's expiry zone): Range: $248.36 - $320.60
- 📅 LEAPS (March 2027 — 360 days): ±$83.17 (±29.24%) → Range: $201.31 - $367.65
Translation for regular folks:
By the weekly expiry this Friday, the market is pricing in a ~3.2% swing in either direction — roughly $9. That puts the weekly ceiling near $293.62 and the floor near $275.34.
The April 17 monthly expiry is the one to watch most closely before earnings on April 27. The market is pricing in an 8.2% swing by then ($23 in either direction), which places the upper range at $307.77 and lower at $261.19.
For the June 18/19 expiry — the actual expiration for today's trade — the implied range stretches from $248.36 to $320.60. The $265 long put the trader bought sits comfortably within the lower half of that implied range, meaning the market already acknowledges a real probability CDNS could trade down there. The $290 short put is right at the current price resistance level.
Key insight: The jump from 3.2% weekly implied move to 8.2% for the April monthly reflects that earnings uncertainty on April 27 is driving a significant vol premium. This is exactly why the trader used June expiry — it clears the earnings event with time to spare.
🎪 Catalysts
🔥 Upcoming Catalysts (What Matters Next)
Q1 FY2026 Earnings — April 27, 2026 (34 days away) 📊
This is the single most important event for this trade. Key metrics to watch per MarketBeat and Nasdaq earnings calendar:
- 💰 Revenue guidance: $1.42B-$1.46B consensus — first quarter with Hexagon D&E revenue (~$40M quarterly run-rate)
- 📈 EPS target: ~$1.89-$1.95 non-GAAP (guided by management on February 17 earnings call)
- 🤖 ChipStack AI commentary: Early access conversion from NVIDIA, Qualcomm, Altera, and Tenstorrent to paid tiers will move the stock
- 🇨🇳 China exposure: Guided at 12-13% of 2026 revenue (~$720-780M) — any hint of tightened export controls is an immediate negative (Silicon.co.uk)
- 📋 Updated FY2026 guidance incorporating Hexagon — first full quarter with Hexagon fully consolidated, per Seeking Alpha
ChipStack AI Super Agent Commercialization (Q2-Q3 2026)
Launched February 10 with NVIDIA, Qualcomm, Altera, and Tenstorrent on early access. Reports of up to 10x productivity gains in chip design workflows. Built on Cadence's November 2025 acquisition of ChipStack technology. Conversion to paid subscriptions is the revenue unlock — still speculative but a potential $50-100M+ incremental revenue at scale per analyst estimates.
DAC (Design Automation Conference) — June 2026
Major annual venue for Cadence product announcements, per StockTitan. Timing aligns with the June 18 option expiry in today's trade. Any product news here could move the stock.
Hexagon D&E Integration Milestones (H1-H2 2026)
Integration of Hexagon's structural analysis, acoustics, and multibody dynamics into Cadence's SDA portfolio. Expected $160M incremental revenue contribution for FY2026 (Manufacturing Dive). Path to EPS accretion in 2027 will be closely tracked.
Photonics / CPO Roadmap (H1-H2 2026)
Lightmatter collaboration progressing toward manufacturing-ready co-packaged optics solutions. Photonic interconnect is an emerging TAM opportunity as AI clusters scale beyond electrical bandwidth limits (Simply Wall St).
Q2 FY2026 Earnings — Late July 2026
First full quarter with complete Hexagon D&E contribution. Will be the cleaner read on integration progress and updated guidance trajectory.
✅ Recent Catalysts (Already Happened)
Q4 FY2025 Earnings Beat (February 17, 2026)
- Revenue $1.44B, beating consensus by 1.1%, up 6.2% YoY
- Non-GAAP EPS $1.99, beating by 4.7%
- Full Year FY2025: Revenue $5.297B (+14% YoY), non-GAAP EPS $7.14 (+20% YoY)
- Record $7.8B backlog entering 2026, covering ~67% of expected revenue
- FY2026 guidance: $5.9B-$6.0B revenue / $8.05-$8.15 EPS — above consensus at time of release
- IP revenue grew ~25% YoY; Core EDA grew ~13% YoY; Hardware posted a record year with 30+ new customers (Futurum Group)
Hexagon D&E Acquisition Closed (February 23, 2026)
- $2.7B EUR deal (~$2.9B), 70% cash / 30% Cadence stock — adds structural analysis, acoustics, multibody dynamics
- $160M incremental 2026 revenue contribution, ~$0.28 EPS dilutive in 2026, accretive in 2027
- All regulatory approvals obtained
NVIDIA Partnership Expansion (March 2026)
- Cadence Millennium M2000 Supercomputer delivering 80x throughput / 20x lower power using NVIDIA Grace CPUs + Blackwell GPUs
- Micron integrating GPU-accelerated Cadence tools into HBM memory design; Honda using Cadence CFD for turbofan simulation (TradingView)
- Full expanded partnership announcement — strengthens Cadence's position as infrastructure layer for agentic AI chip design
Flexcompute PhotonForge Connector (March 19, 2026)
- GPU-accelerated photonic simulation integrated into Cadence Virtuoso Studio for AI data center design
- Deepens Cadence's role in co-packaged optics (CPO) and photonic interconnect, a growing TAM as AI cluster bandwidth demands scale
Lightmatter Photonics Collaboration (January 26, 2026)
- Co-developing co-packaged optics solutions integrating Cadence's high-speed SerDes and UCIe IP with Lightmatter's Passage optical engine — targets hyperscaler custom AI infrastructure chips
- Positions Cadence at the forefront of the photonic interconnect TAM as AI clusters scale beyond electrical bandwidth limits (Yahoo Finance)
Analyst Upgrades & Price Targets (February-March 2026)
- Rosenblatt upgraded to Buy with $360 target; Stifel reiterated Buy at $395
- Morgan Stanley cut PT from $385 to $370 (Overweight maintained); Piper Sandler cut from $355 to $319 (Neutral)
- Consensus: 17 Strong Buy, 1 Moderate Buy, 5 Hold. Average price target: $371.82 — implying ~30% upside from current levels
📐 Price Targets & Probabilities
Using the gamma map and implied move data together with catalyst timing:
🐻 Bear Case Floor — $265 This is the long put strike from today's trade and the third-strongest put gamma level (0.23B). The April monthly implied move lower bound is $261.19. If Q1 earnings disappoint on April 27 — particularly on China revenue, Hexagon dilution guidance, or ChipStack adoption — a flush to $265 is the scenario the institutional trader is hedged against. Below $265 and their long puts start paying out dollar-for-dollar.
📊 Base Case Range — $280-$290 The gamma compression zone. CDNS has been grinding in this area and is likely to stay range-bound until the April 27 earnings catalyst. The $280 put gamma support acts as a floor; $290 call-dominated resistance is the ceiling. Short-term, this is the expected range per implied move data (weekly: $275-$293).
🚀 Bull Case Target — $300-$310 The $300 level has the heaviest call gamma on the board (1.83B total). A strong earnings beat on April 27 — particularly a guidance raise incorporating Hexagon and strong ChipStack adoption commentary — could propel CDNS to challenge $300. Consensus analyst price target sits at $371.82 with 17 Strong Buy ratings, implying analysts see significant recovery potential. $300-$310 is realistic on a re-rating catalyst in the near term.
💡 Trading Ideas
🛡️ Conservative — "The Sleep Well Strategy"
Position: Buy the June 2026 $280/$270 Bull Put Spread
How it works: Sell the $280 put, buy the $270 put, same June 18 expiry. Collect a credit while staying defined-risk.
- 💰 Approximate cost: Net credit of
$3-4 per spread ($1.40-$1.50 credit collected) - 📈 Profit if: CDNS stays above $280 through June 18 (currently ~2.1% above current spot at $285.97)
- ❌ Max loss: Limited to $10 minus credit received (~$6-7 per spread)
- 🎯 Why this works: You're aligned with the gamma picture — $280 is the nearest strong support level. The June expiry clears Q1 earnings. Even if CDNS pulls back modestly, $280 has significant put gamma acting as a floor. The trade expresses a "CDNS doesn't crater further" view without betting on a big rally.
- ⚠️ Risk: China export control escalation or a Q1 earnings miss that pushes CDNS below $280
⚖️ Balanced — "Ride the Earnings Bounce"
Position: Buy the May 2026 $290 Call (post-earnings expiry)
How it works: Buy a single call just above current resistance at $290, expiring after the April 27 earnings.
- 💰 Approximate cost: ~$8-10 per contract
- 📈 Profit if: CDNS rallies above $298-$300 after earnings (roughly 5-7% move from current levels)
- ❌ Max loss: The premium paid — defined risk
- 🎯 Why this works: With 17 Strong Buy ratings and an average analyst price target of $371.82, CDNS at $286 is arguably deeply discounted. The $290 strike aligns with the key resistance level where today's big trade sold puts — if the stock breaks above that, there's a clean run toward the $300 gamma ceiling. This play costs much less than buying stock but captures a solid earnings re-rating move.
- ⚠️ Risk: Earnings in-line or miss; any China export control headline before April 27. If CDNS stays range-bound, the call expires worthless.
🚀 Aggressive — "The Gamma Squeeze Play"
Position: Buy the April 17 $290/$300 Call Debit Spread
How it works: Buy the $290 call, sell the $300 call — expires right before Q1 earnings on April 27. This is a pure pre-earnings momentum play.
- 💰 Approximate cost: ~$3-4 per spread
- 📈 Maximum profit: Up to $10 per spread (~150-200% return) if CDNS closes above $300 by April 17
- ❌ Max loss: Full spread cost if CDNS stays below $290
- 🎯 Why this works: The $300 level has 1.83B gamma — the single strongest level on the board. Pre-earnings momentum often pushes stocks toward high-gamma resistance levels as market makers delta-hedge. You're buying into the $290-$300 range that is both implied-move-accessible (April upper range: $307.77) AND aligned with the heaviest call gamma cluster. The spread structure limits your cost.
- ⚠️ Risk: This expires BEFORE earnings — it's a momentum / volatility expansion trade, not an earnings bet. If CDNS drifts sideways or lower in the 3 weeks before April 17, the spread decays to zero. High risk of total loss on the premium.
⚠️ Risk Factors
🇨🇳 China Export Controls — The Wildcard
Cadence paid a $140M+ combined DOJ/BIS penalty in July 2025 for unauthorized EDA exports to Chinese military-linked entities. The FY2026 guidance explicitly assumes export controls remain "broadly unchanged" — with China representing 12-13% of revenue (~$720-780M), any policy tightening is an immediate negative catalyst. A May 2025 BIS ban on EDA exports to China was partially reversed in July 2025 — the policy environment remains genuinely uncertain.
📉 Valuation Compression Risk
At ~72x P/E, CDNS has essentially no margin for error. Any guidance miss, deceleration in backlog growth, or macro-driven multiple compression could extend the current drawdown further below the implied move lower bounds.
🏗️ Hexagon Integration Execution
The $2.7B acquisition closed February 23, 2026. Integration of structural analysis, acoustics, and multibody dynamics into Cadence's SDA portfolio is complex. $0.28 EPS dilution in 2026 — if integration stumbles, the path to 2027 accretion gets murkier and analysts may lower price targets.
🤖 ChipStack Monetization Timeline
The ChipStack AI Super Agent is still in early access. Productivity claims of up to 10x are compelling, but converting NVIDIA and Qualcomm from early access to paid subscriptions at scale is unproven. If April 27 earnings commentary on adoption is cautious, it could disappoint AI-themed investors.
💼 Institutional Selling
Nordea Investment Management trimmed 318,632 shares in Q4 2025. While overall institutional ownership remains high at 84.9%, continued de-risking ahead of earnings could create selling overhang.
⏰ The Trade Itself Has Real Risk
The $290/$265 put spread structure means today's institutional trader risks up to $20.8M if CDNS falls below $265 by June 18. That's not a sure-thing trade — it's a conviction bet that CDNS either stays near current levels or recovers meaningfully into the June expiry.
🎯 The Bottom Line
Real talk: The $38.2M put spread in CDNS today is a well-constructed, defined-risk institutional position that tells two stories simultaneously: either a sophisticated player is expressing a "CDNS stays above $290 by June" view and collecting $4.2M in net premium to do it — or it's a hedge protecting a large long position ahead of what could be a binary April 27 earnings report.
The gamma and implied move data are consistent: CDNS is range-bound between $280 and $290 right now, with the real volatility catalyst being Q1 earnings on April 27. The implied move prices in an 8.2% swing by April 17 OPEX — meaning a move to $307 on the upside or $261 on the downside is within the options market's expected range.
Three scenarios:
-
🚀 If you're bullish: The fundamental picture is genuinely strong — record $7.8B backlog, completed Hexagon deal, NVIDIA partnership, and an average analyst price target of $371.82 from 17 Strong Buy ratings. A stock 22% off highs with improving fundamentals has historically been a setup to accumulate, not avoid. The bull put spread or call play captures that view.
-
👀 If you're waiting: Mark your calendar for April 27, 2026. That's the moment everything crystallizes — Hexagon Q1 contribution, ChipStack adoption commentary, China revenue update, and updated full-year guidance. Going into that event without a clear directional view means sitting in cash is a perfectly valid position.
-
😰 If you're cautious: The China export control risk is real and binary. The $140M penalty history and the "broadly unchanged" assumption baked into FY2026 guidance means any adverse policy news before or during earnings could gap the stock down hard. The June $265 puts bought today could become very valuable in that scenario.
One thing is clear: when a single player moves $38M in a structured spread at the exact moment the stock is sitting between its two strongest gamma levels, it's worth paying attention. This isn't random flow. Someone with a large view and the capital to back it just made their move.
⚠️ Disclaimer: This analysis is for informational and educational purposes only. Options trading involves substantial risk and is not suitable for all investors. You can lose the entire amount invested in options. Past unusual options activity does not guarantee future price movement. Always do your own research and consult a financial professional before trading. The trades described above represent unusual options activity and do not constitute a buy or sell recommendation.