⚡ IREN $3.9M Jan-2028 LEAP — Whale Targets the $110 Convertible Cap on AI Datacenter Pivot
📅 May 26, 2026 · Last updated: 2026-05-27 (OI ✅ confirmed) | 🔥 Unusual Activity
✅ OI RESOLVED 2026-05-27: OI on the Jan 2028 $110 LEAP rose from 37,970 → 40,233 (Δ +2,263), consistent with the 2,000-contract block opening fresh long calls. BTO confirmed. Pre-market OI 37,970 → 40,233 (Δ +2,263). BTO HIGH confidence.
🎯 The Quick Take
Someone just dropped $3.9 MILLION on IREN January 2028 $110 calls — a 20-month LEAP sitting ≈84% above today's price. This isn't a lottery ticket: the $110 strike is the exact cap price on IREN's recently-issued convertible notes capped-call hedge, meaning the buyer is explicitly targeting the scenario where IREN's stock doubles from here and blows through its own dilution protection. With Microsoft's $9.7B cloud contract and NVIDIA's $3.4B anchor deal in the pipeline, this is a deliberate "double-or-nothing" bet on IREN's full AI datacenter pivot executing on schedule.
🏢 Company Overview
IREN Limited (NASDAQ: IREN) — operating as Iris Energy — was born as a green Bitcoin miner but is now executing one of the most aggressive pivots in the datacenter sector:
- Market Cap: ≈$21.5 billion (as of May 26, 2026)
- Industry: Datacenter / AI HPC Infrastructure (formerly Bitcoin Mining)
- Current Price: $59.81 intraday | $59.38 close
- YTD Performance: +50.46% (as of May 22, 2026)
- Primary Business: Rapidly transitioning from Bitcoin mining (still 77% of Q3 revenue) to large-scale GPU cloud services anchored by Microsoft and NVIDIA contracts, with ≈5GW of energized or near-energized power infrastructure across Texas, British Columbia, and West Texas
💰 The Trade — $3.9M LEAP, ≈84% OTM, $110 Strike
Real talk: somebody walked up and paid $3.9 million for 2,000 contracts of IREN January 2028 $110 calls in the middle of a Tuesday afternoon. That's not hedging. That's a conviction bet with a 20-month runway — enough time for two full earnings cycles, multiple GPU deployment tranches, and the full ramp of IREN's Microsoft and NVIDIA contracts.
The Vol/OI ratio on this trade is just 0.137 — volume is only a fraction of the 38,000 existing contracts at that strike — which means there's already substantial open interest at $110 from traders who had the same thesis before today. This buyer is adding to an existing army, not going alone.
At $19.39 per contract ($1,939 per 100-share contract), with the stock at $59.81, the option needs IREN to roughly double just to get in-the-money at expiration. That is an aggressive target — and it's an intentional one.
📊 Full Trade Details
| Field | Detail |
|---|---|
| Date | May 26, 2026 |
| Time | 14:04:16 ET |
| Exchange | MID (CBOE) |
| Ticker | IREN |
| Side | BUY (Ask-side — paid up) |
| Option Type | CALL |
| Order Type | BTO (Buy to Open — new long position) |
| Strategy | Long Call (LEAP) |
| Strike | $110 |
| Expiration | 2028-01-21 (≈20 months) |
| Option Price | $19.39 per share |
| Total Premium | $3,900,000 |
| Volume | 5,200 contracts |
| Position Size | 2,000 contracts (≈$3.9M) |
| Open Interest | 38,000 contracts |
| Vol/OI Ratio | 0.137 (adding to existing large OI base) |
| Spot at Trade | $59.81 |
| Closing Price | $59.38 |
| Distance OTM | ≈84% above spot |
| Days to Expiry | ≈600 days |
🎯 Why $110 Specifically — The Convertible Capped-Call Connection
This is the most important detail in this entire trade, and it's not a coincidence.
On May 11, 2026, IREN priced $2.6 billion of 1.00% convertible senior notes due 2033 (upsized from $2.0 billion with a $400 million greenshoe). To protect existing shareholders from dilution, IREN used $201.3 million of proceeds to purchase a capped-call overlay — essentially an option structure that limits dilution from the convertible notes up to a specific share price.
That cap price is $110.30 per share.
Translation for regular folks: the convertible notes will convert into shares at $73.07, but IREN has hedged the dilution all the way up to $110.30. Above that price, the capped-call protection expires and shareholders face uncapped dilution from the convertible notes. The options market knows this, which is why there's already 38,000 contracts of open interest at exactly the $110 strike.
The whale buying today is making a deliberate, informed bet: IREN breaches $110, the convert protection expires, and the stock has already doubled. At that point, the dilution math almost doesn't matter because the business has executed its AI ramp well enough to justify the price.
🚀 The Anchor Contracts — Microsoft $9.7B + NVIDIA $3.4B
Buckle up, because IREN's contract stack is unlike anything seen in the ex-mining space.
Microsoft $9.7B, 5-Year GPU Cloud Contract:
Announced November 3, 2025, this five-year agreement gives Microsoft access to NVIDIA GB300 GPUs at IREN's 750MW Childress, Texas campus with a 20% upfront prepayment. Data Center Dynamics confirms deployment across 200MW of critical IT load through four liquid-cooled data centers (Horizon 1–4). Management projects ≈$1.9B average annual revenue contribution from this contract alone per Q3 FY26 disclosures.
NVIDIA $3.4B, 5-Year + 30M Share Warrant:
The deal announced concurrent with Q3 earnings has three layers: a $3.4B managed GPU cloud services contract for NVIDIA's internal AI/research workloads across ≈60MW at Childress, a 5-year warrant for NVIDIA to acquire up to 30 million IREN shares at $70 (fully exercised = ≈$2.1B equity commitment tied to GPU delivery milestones), and a collaborative pipeline of up to 5GW of NVIDIA-DSX-aligned AI infrastructure. Per Q3 8-K SEC filing, the NVIDIA contract contributes ≈$0.7B of expected average annual revenue.
Combined contracted revenue: $13.1 billion across Microsoft + NVIDIA — the largest hyperscaler-anchored contract stack among all ex-mining datacenter operators per CoinShares Q1 2026 data.
The LEAP buyer's thesis: if both contracts execute on schedule and IREN secures even one additional hyperscaler (management has hinted at advanced discussions), the path to $110+ becomes a realistic probability, not just a tail scenario.
📈 YTD Context — +50% and Still Building
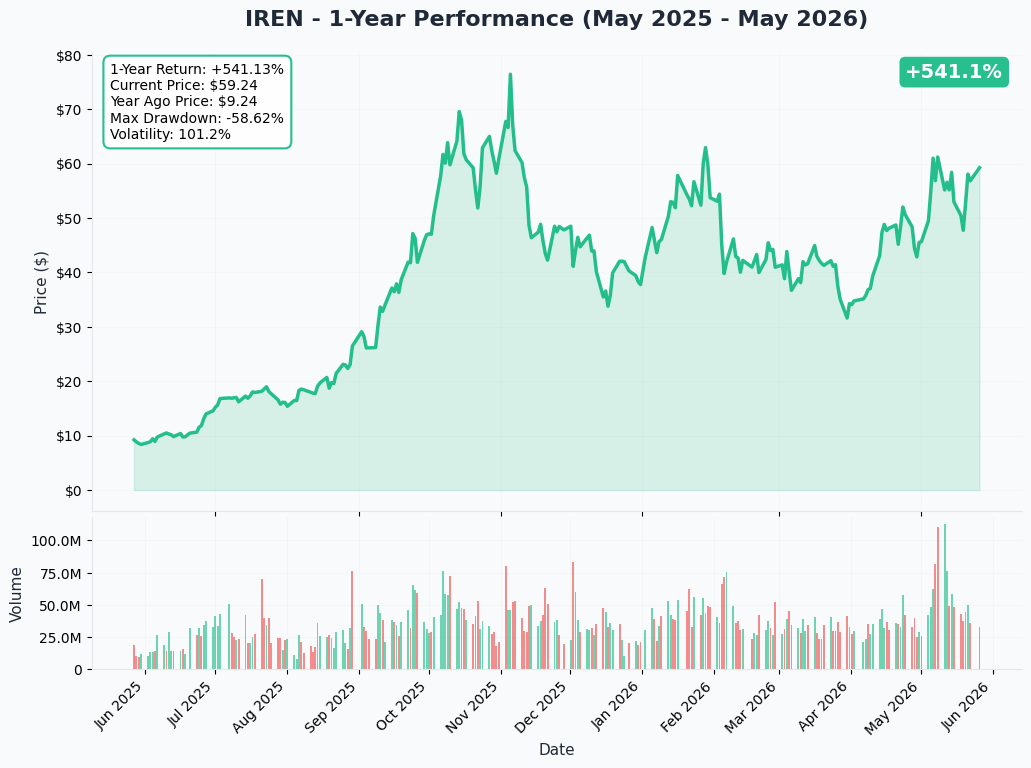
IREN is up +50% year-to-date as of May 22, 2026 — one of the strongest performers in the datacenter and mining crossover space. The rally has been driven almost entirely by contract announcements: the Microsoft deal provided the first leg, and the NVIDIA partnership plus the $2.6B convertible raise in May provided the second.
The stock started 2026 near $40, climbed sharply on the NVIDIA deal announcement (shares surged 13–27% in after-hours per Yahoo Finance), then partially gave back the gains on the Q3 FY26 revenue miss before stabilizing in the $58–$62 range.
Key observation: despite a 34% revenue miss in Q3, the stock has held its gains. That is a bullish market signal — investors are looking through the mining decommissioning pain to the AI ramp.
📉 Q3 FY26 — The Bull-Bear Pivot Quarter
The Q3 FY26 earnings released May 7, 2026 were messy on the surface but clarifying underneath:
- 📉 Total revenue: $144.8M vs. $219.87M consensus — a 34.1% miss
- 📉 Bitcoin mining revenue: $111.2M, down 33.6% sequentially — IREN is aggressively decommissioning miners to free Childress capacity for GPUs
- 📈 AI Cloud Services revenue: $33.6M, +94.2% QoQ vs. $17.3M in Q2 — the number that matters
- 📉 Net loss: $(247.8)M, including $140.4M of non-cash impairments from retired mining hardware (SEC 8-K)
- ✅ Cash position: $2.6B at April 30, 2026 — the company is not in financial distress
The math problem is stark. AI Cloud at $33.6M/quarter equals roughly $134M annualized. IREN is guiding to $3.7B annualized AI Cloud ARR by end of 2026 — an approximately 28x ramp in 9 months. That is an aggressive target. The LEAP buyer is betting it arrives on schedule. The bears are betting it doesn't.
Also on May 1, 2026, IREN successfully energized the Sweetwater 1 substation — a 1.4GW facility in West Texas connecting to ERCOT. Sweetwater 2 (600MW) targets late 2027, giving IREN a 2GW combined hub capable of supporting over 700,000 liquid-cooled GPUs. Power capacity is the scarcest resource in AI right now, and IREN owns a lot of it.
🤔 Analyst Split — JPMorgan Underweight vs. Cantor Overweight
The street is genuinely divided on IREN, and both sides have legitimate points:
Bears (JPMorgan, May 11, 2026): Raised price target to $46 from $39 but maintained Underweight, citing the "circular" structure of the NVIDIA deal — NVIDIA receives a warrant for IREN equity and simultaneously sells GPUs to IREN, who then rents capacity back to NVIDIA. JPMorgan's concern: warrant proceeds partially recycle back to NVIDIA via GPU purchases, questioning the true cash quality. Their $46 target sits ≈23% below today's price.
Bulls (Cantor Fitzgerald): Maintained Overweight with $61 price target despite a cut from $82 — still sees upside from current levels.
Consensus (May 25, 2026): 11 analysts rate Buy, median price target $80, range $41–$105 per TipRanks. Notably, the high-end analyst target of $105 is approaching the $110 LEAP strike territory.
The LEAP buyer is siding with the bulls — and then betting on an outcome even more aggressive than the most bullish analyst on the street.
📊 Gamma Exposure — $110 Has Its Own Wall
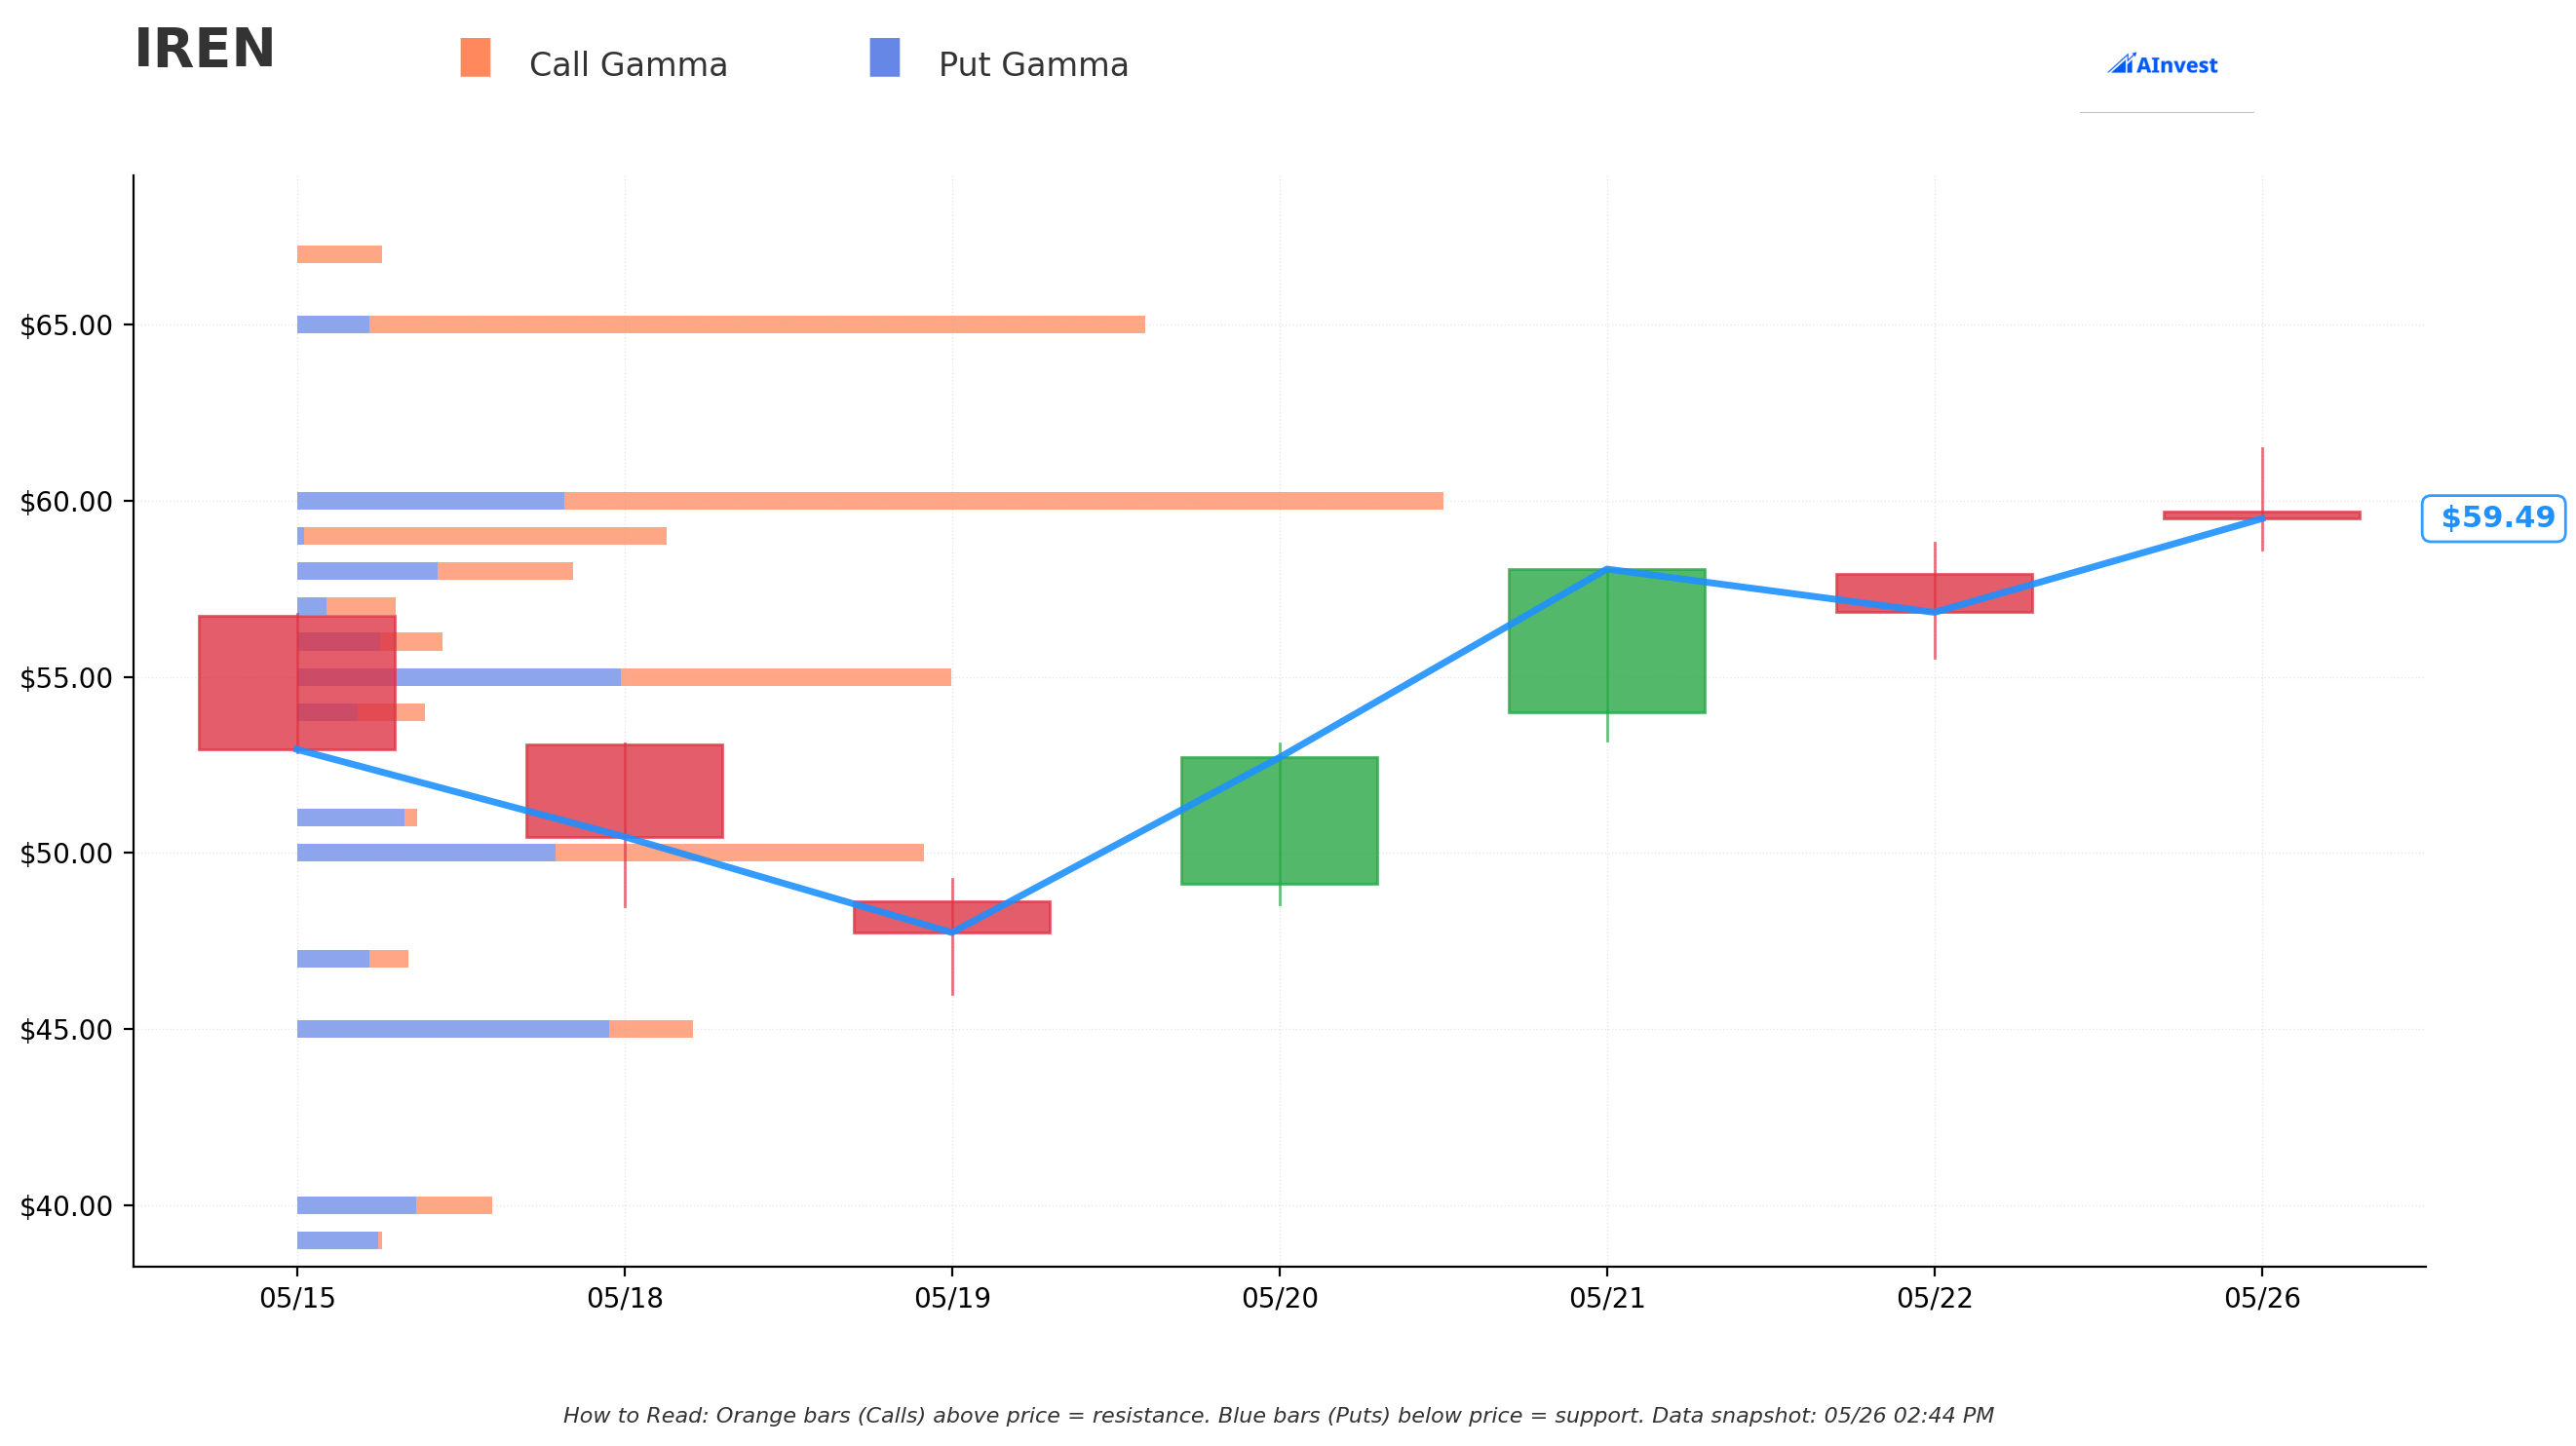
The gamma exposure map tells a fascinating two-part story:
Near-term levels (governing the next few weeks):
🟠 $60 — Very Strong Resistance (total GEX: 13.41): IREN is pinned right below $60, just $0.79 away. This is the single largest gamma concentration in the entire chain. Market makers are heavily short calls at this strike and will sell into any rally toward $60, creating a mechanical ceiling. Until this level flips, the stock needs a meaningful catalyst to break higher.
🟠 $65 — Secondary Resistance (total GEX: 9.88): The next ceiling after $60, requiring a ≈10% move from spot.
🟠 $70 — Third Resistance (total GEX: 7.41): Interestingly, this is also the NVIDIA warrant exercise price — if the stock approaches $70, NVIDIA begins to have economic incentive to exercise tranche milestones.
🔵 $59 — Moderate Support (total GEX: 4.38): Immediate floor, just $0.21 below spot at the time of the gamma snapshot.
🔵 $55 — Strong Support (total GEX: 7.74): The next meaningful floor, ≈7% below current levels.
🔵 $50 — Support Wall (total GEX: 7.40): Deep support, ≈15% lower.
The $110 detail: The gamma data shows a Resistance Wall at $110 with total GEX of 6.03 — meaning market makers are already short calls at that strike in substantial size. If IREN ever approaches $110, dealers who are short those calls will need to buy shares aggressively to hedge their delta exposure, which would accelerate the move toward $110. This is the gamma "squeeze" scenario the LEAP buyer is implicitly betting on.
📅 Implied Move Analysis — The 20-Month Runway
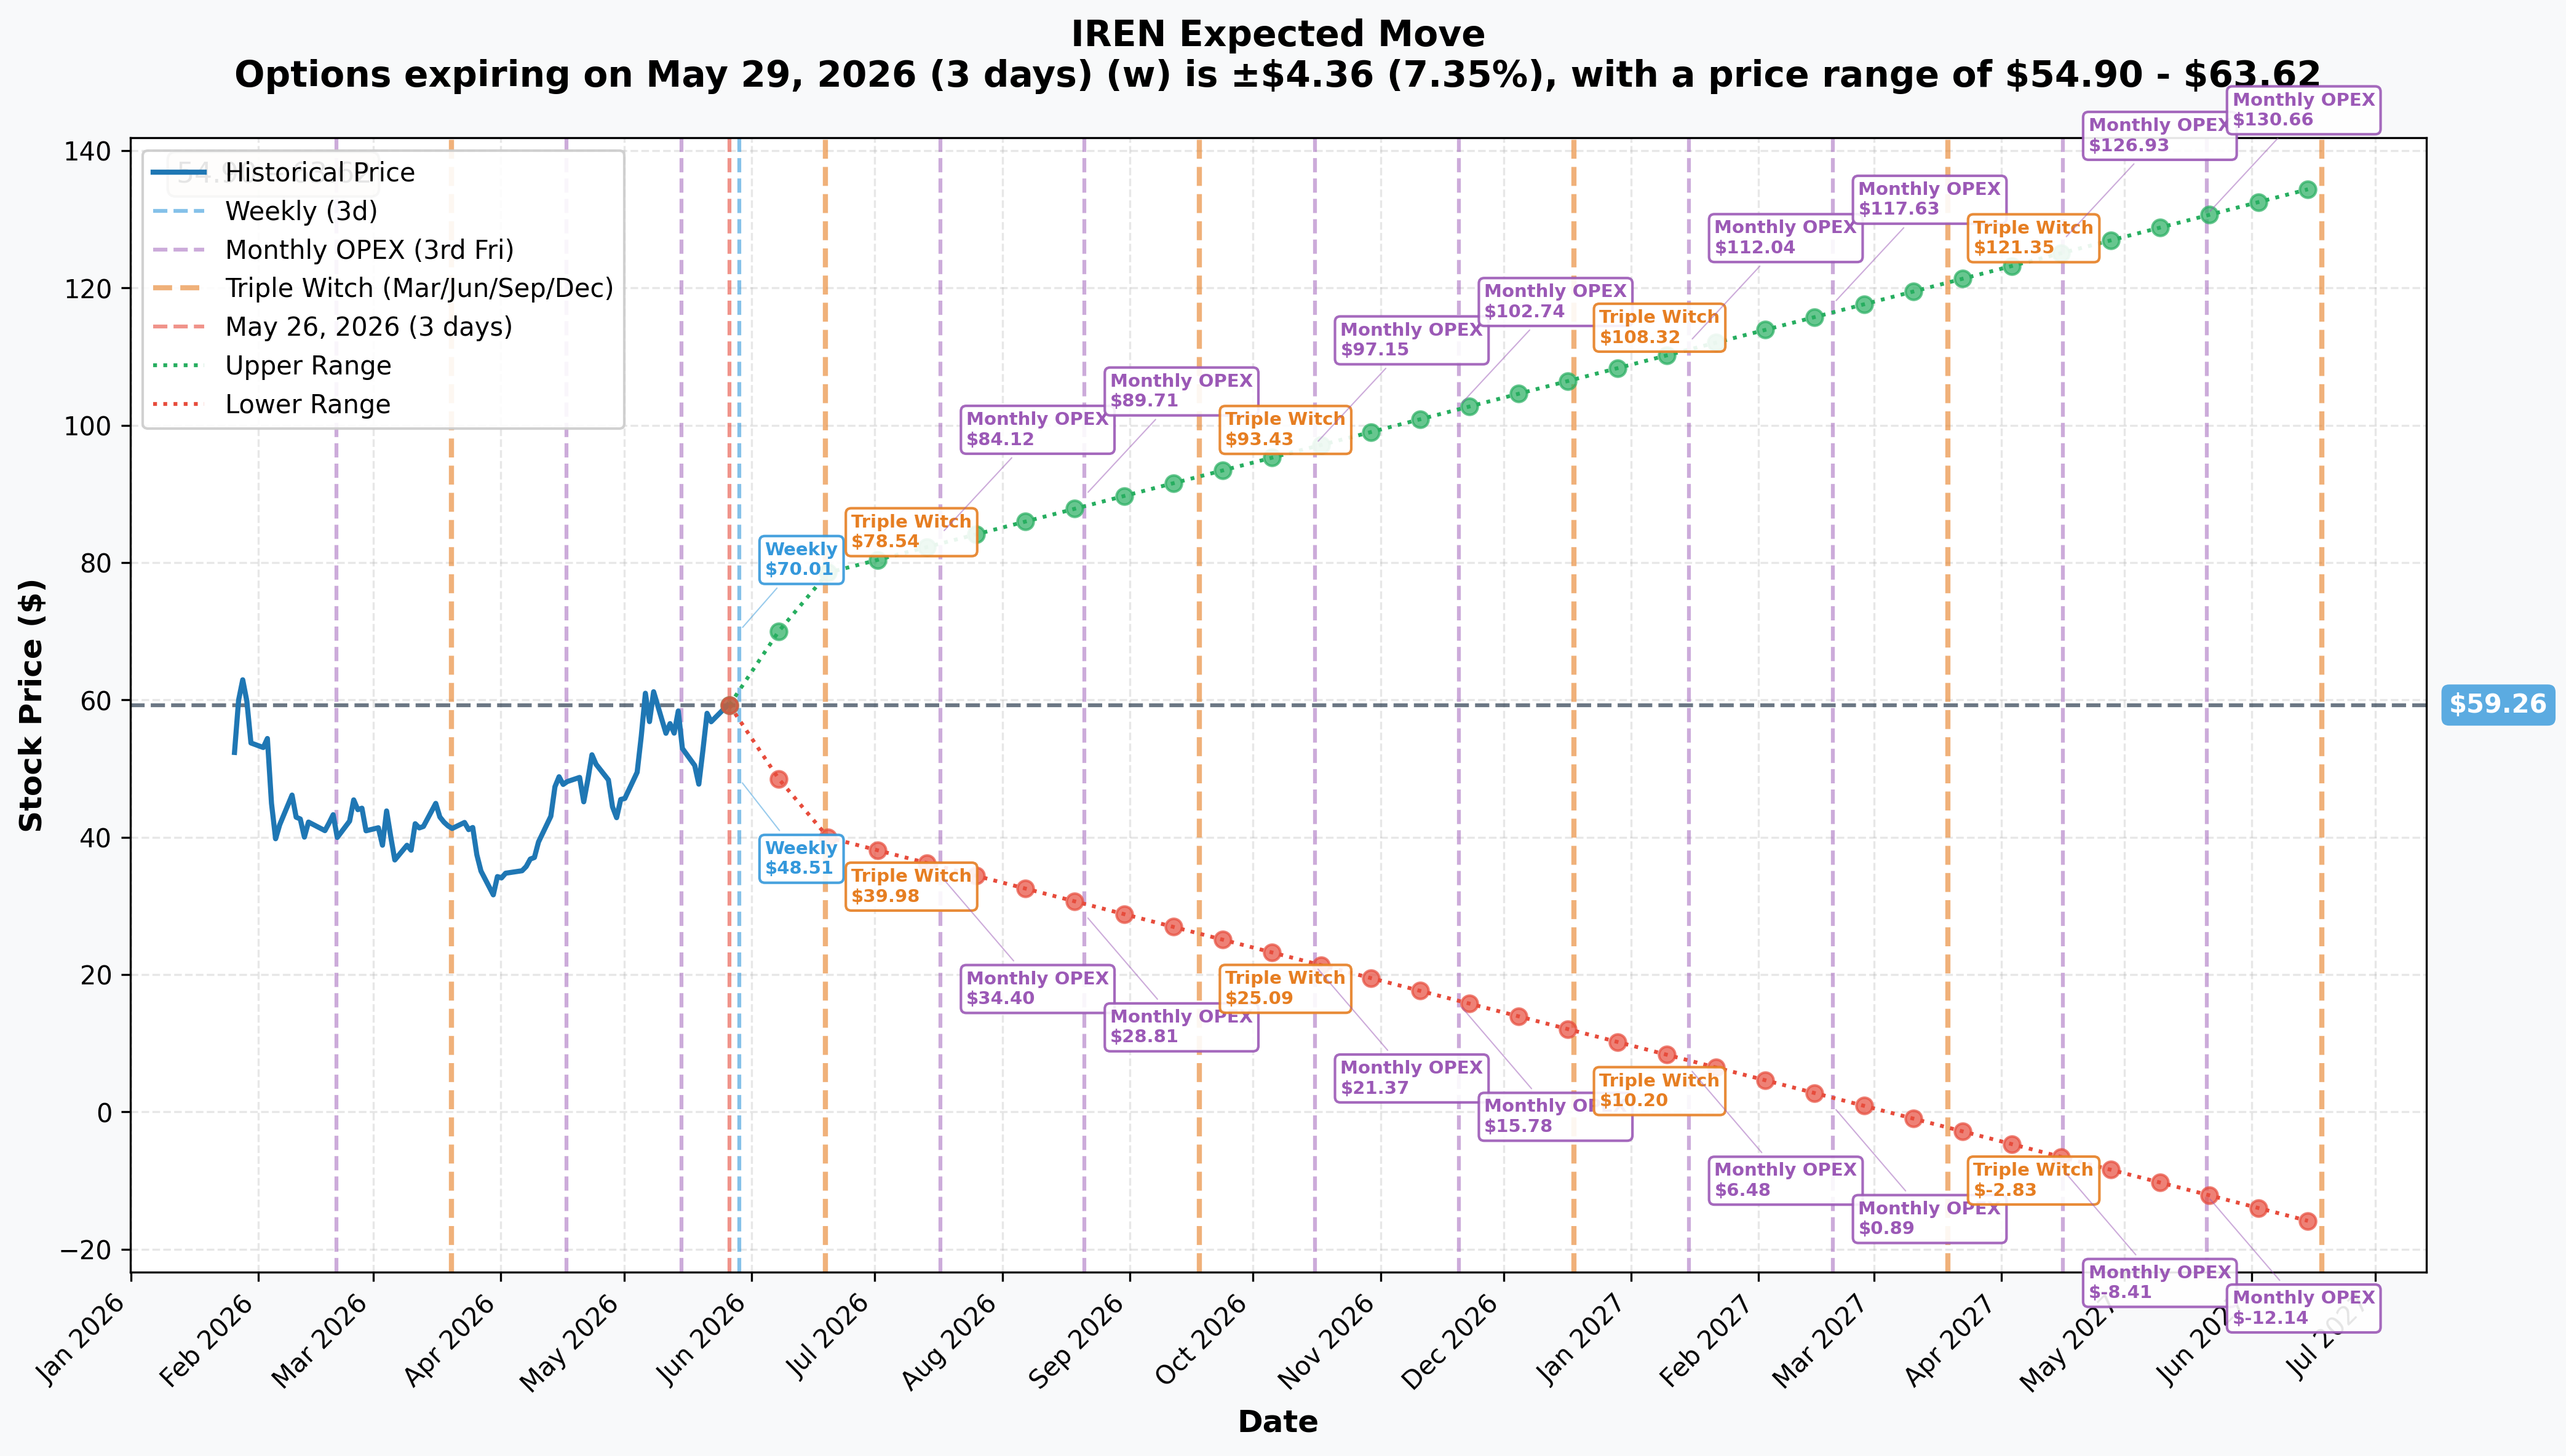
The options market is pricing in extraordinary uncertainty for IREN across all timeframes:
- 📅 Weekly (May 29 — 3 days): ±$4.36 (±7.35%) → Range: $54.90 – $63.62
- 📅 Monthly OPEX (June 19 — 24 days): ±$19.28 (±32.54%) → Range: $39.98 – $78.54
- 📅 July 17 OPEX (52 days): implied upper $84.12, lower $34.40
- 📅 August 21 OPEX (87 days — next earnings ≈ Aug 27): implied upper $89.71, lower $28.81
- 📅 December 18 Triple Witch (206 days): implied upper $108.32, lower $10.20 — the $110 strike begins to enter the implied range here
- 📅 January 15, 2027 OPEX (234 days): implied upper $112.04 — the Jan 2028 LEAP strike clears the 1-year implied move upper band
The key takeaway: by December 2026 (7 months away), the market is already pricing a realistic probability of IREN trading at $108+. By January 2027, the upper implied range eclipses $112. The LEAP buyer is buying time — 20 months of time — for the implied move range to catch up to the $110 strike organically.
The yearly LEAP implied move (through June 2027) is ±127.8% — meaning the market is pricing a scenario where IREN could reach $135 in one year, or go nearly to zero. This reflects the genuine binary nature of IREN's AI pivot.
⚠️ Risk Factors — What Could Go Wrong
This is a high-conviction bet with real execution risk. Here's what the LEAP buyer is betting doesn't happen:
1. AI Cloud ramp slips by even one quarter. Going from $134M annualized to $3.7B ARR in ≈9 months requires near-flawless GPU delivery from NVIDIA (B300 GPUs), energization of Horizon 1–4 at Childress, and customer ramp. IREN has signed purchase agreements for over 50,000 NVIDIA B300 GPUs in deployment phases through H2 2026. Any GPU delivery delay cascades through revenue recognition — and IREN's stock would likely revisit the $40s.
2. Bitcoin mining still 77% of revenue. The Q3 miss was mostly driven by lower BTC prices and mining decommissioning. If BTC prices fall materially while the AI ramp is still early, IREN's headline financials look ugly even if the transition is on track. Per CoinDesk reporting, public miners are broadly selling BTC reserves to fund the AI pivot — which can create self-reinforcing downside for BTC.
3. The dilution stack is heavy. Above $110.30, the capped-call protection expires on the $2.6B convertible notes. Additionally, IREN has a $6B at-the-market shelf filed with the SEC, and NVIDIA holds warrants for up to 30 million shares at $70. The cumulative convertible debt now totals ≈$3.7B per peer analysis. Sustained share issuance above $70–$110 could pressure the stock even as the business succeeds.
4. JPMorgan's circular deal concern. The JPMorgan critique that NVIDIA proceeds recycle back to NVIDIA via GPU purchases is a legitimate structural concern. If institutional investors adopt this view broadly, multiple compression could limit upside even if execution is solid.
5. ERCOT and power regulatory risk. Texas grid (ERCOT) regulatory environment for large-load AI data centers remains in flux. Childress liquid-cooled retrofit and Sweetwater 2 (targeted late 2027) both require continued ERCOT interconnect approvals.
Maximum loss on this trade: $3.9 million (100% of premium). If IREN is below $110 on January 21, 2028, these contracts expire worthless.
💡 What Does This Mean for You? — 4 Perspectives
🚀 YOLO Trader
The whale paid $19.39 per contract for a LEAP with an 84% OTM strike. The leverage is real — if IREN reaches $130 by January 2028, the $110 call would be worth ≈$20+ intrinsic value alone. But this is not a weekly play. If you're chasing this trade with near-dated OTM calls, you're playing a different (and far more dangerous) game. The 20-month time horizon is load-bearing.
⚖️ Swing Trader
The near-term gamma structure pins IREN at $60 with strong resistance. A near-term entry into the stock (not the LEAP) between $57–$59 (gamma support at $59/$55) with a target at $65 resistance makes more sense than chasing the 84% OTM trade. Watch Q4 FY26 earnings on ≈August 27 — if AI Cloud revenue inflects toward $80M+ for the quarter, that's the first concrete confirmation of the ramp thesis.
🛡️ Premium Collector
With implied volatility this elevated (the monthly OPEX implies ±32% range in 24 days), selling covered calls at $65 or $70 against a stock position collects meaningful premium while participating in the first leg of any rally. The risk: IREN gaps through your call strike on a hyperscaler announcement. Use short-dated weeklies rather than monthlies to manage this.
📚 New to Options
Here's the plain-English version: someone bought the right to purchase IREN shares at $110, and they paid $3.9M for that right. IREN trades at $59.81 today. For that trade to profit, IREN needs to roughly double in the next 20 months. The buyer thinks that's possible because IREN has signed $13.1 billion in AI cloud contracts with Microsoft and NVIDIA. The risk is that if IREN doesn't reach $110 by January 2028, all $3.9 million is gone. This is a high-risk, high-reward speculation — not suitable as a primary position for most investors.
🎯 The Bottom Line
Here's the deal: The $3.9M LEAP buyer at $110 is not making a random bet. They identified the most technically meaningful price level on IREN's entire cap table — the capped-call cap from the May 11 convert — and purchased 20 months of exposure to that exact scenario. That's sophisticated positioning, not noise.
The bull case is genuinely compelling: Microsoft and NVIDIA have committed $13.1 billion in contracted revenue, IREN owns 5GW of power infrastructure that is the scarcest resource in AI, and the stock has already absorbed a painful Q3 revenue miss without breaking its uptrend.
The bear case is equally legitimate: the $3.7B ARR target requires a 28x revenue ramp in 9 months from a base where Bitcoin mining still accounts for 77% of revenue, a $6B ATM shelf and $3.7B in convertibles overhang the capital structure, and JPMorgan's "circular deal" critique of the NVIDIA structure deserves weight.
If you own IREN: The $60 gamma wall is your near-term ceiling. The $55 support is your near-term floor. Q4 FY26 earnings (≈August 27) are the next binary event — if AI Cloud revenue inflects sharply toward $80M+, the $65–$70 range opens up and the LEAP thesis starts working.
If you're watching from the sidelines: The $58–$59 gamma support zone offers a better-defined entry than chasing at $60 resistance. Set your thesis on the Q4 earnings: if AI Cloud revenue doesn't show material acceleration, the $40s are still in play per JPMorgan.
Mark your calendar:
- 📅 June 19, 2026 — Triple Witch OPEX; implied range $40–$79
- 📅 Mid-July 2026 — Monthly operational update (BTC production + AI Cloud KPIs)
- 📅 ≈August 27, 2026 — Q4 FY26 / Full-Year earnings (consensus EPS −$0.34); KEY inflection for the LEAP
- 📅 H2 2026 — NVIDIA B300 GPU delivery tranches and NVIDIA warrant exercise milestones
- 📅 Late 2027 — Sweetwater 2 energization (600MW)
- 📅 January 21, 2028 — LEAP expiration
The $110 strike is sitting in the December 2026 implied move upper range and just above the January 2027 implied upper of $112. The implied move math says it's not impossible — it's just priced for perfect execution. Whether that execution arrives is the only question that matters.
Disclaimer: Options trading involves substantial risk of loss and is not suitable for all investors. This analysis is for educational and informational purposes only and does not constitute financial advice. The whale trade described reflects a single market participant's positioning, which may include complex hedging or institutional strategies not applicable to retail traders. Deep OTM LEAPs like the $110 January 2028 IREN call can expire completely worthless if the underlying does not reach the strike price. Always do your own research and consult a licensed financial advisor before trading. Past unusual options activity does not guarantee future price movement.
About IREN Limited: Iris Energy (IREN) is a NASDAQ-listed AI infrastructure and Bitcoin mining company pivoting to large-scale GPU cloud services, with ≈$21.5B market cap, 5GW of global power infrastructure, and $13.1B in contracted AI cloud revenue from Microsoft and NVIDIA. Sector: Datacenter / HPC Infrastructure (formerly Bitcoin Mining).