📊 Ainvest Option Flow Digest - 2026-06-12 — The $362M Headline That's Really ≈$86M: Two Giant "Call Buys" Are Hedged Financing, Not Bets
📅 Friday, June 12, 2026 | 🔥 11 structures, ≈$362M printed — but ≈$276M of it (INTC + GLW) is delta-neutral financing, not a directional bet
Last updated: 2026-06-15
🔄 Updated 2026-06-15 — this session's provisional flags are now resolved by next-day OPRA OI. One inversion: MRK was NOT a cautiously-bullish diagonal open — the Sep $100C BUY leg resolved as a CLOSE (OI −4,050) while the Dec $105C short opened (STO), so the desk was reducing call exposure and selling December upside (a de-risking / overwrite repositioning, neutral-to-mildly-bearish). One clarification: AMZN's $295 short leg net-closed (STC, OI −13,909), reframing the print as a bullish roll down rather than a fresh capped spread (thesis still bullish). Everything else opened as described — ABVX, ACMR (Jun-18 leg), CIFR (both puts), GLW + INTC (delta-neutral opens), MSFT (all legs; the $450C prior-OI baseline was corrected from a bad "2" feed value to 11,615), PRIM, SMH, and STM (its provisional $80C resolved as an OPEN, not a close). Per-ticker tables are in each article.
🧮 Read the structure, not the dollar sign — today is the perfect lesson. The two biggest headlines, INTC ($242M) and GLW ($34M) "deep-ITM call buys," are NOT bullish bets. Each is a delta-neutral package: the call cross was paired with a simultaneous short-stock block (INTC: 5,000,000 shares @ $125; GLW: 520,000 shares @ $176.50) that cancels the delta. They're synthetic-put / financing trades. Strip those ≈$276M out and the genuinely directional flow is ≈$86M — and it leans bullish on semis and construction (SMH, ACMR, STM, PRIM, AMZN, MRK), with one bearish crypto-miner put (CIFR), a biotech lottery (ABVX), and a genuinely split MSFT (a bullish call spread AND a $22M downside put).
🔁 OI Review — Last Session's Provisional Flags, Now Resolved (Updated 2026-06-12)
The next-day OPRA OI snapshot for Thursday 2026-06-11 is in, and it carried two clean inversions plus a big-ticket close. Both of yesterday's "bullish" calls were actually exits, and the day's largest print — a $35M gold put — was a hedge being unwound. The only genuinely new positioning was bearish/defensive, and all of it opened. The standout lesson: a bad OI feed turned a close into a fake "confident bullish open."
🔄 Inversions — The Same-Day Read Flipped
- AMZN 6/11 — $12M $240 call: OI FELL 15,670 → 8,320 (Δ −7,350 ≈ the 7,500 traded). Read same-day as a confirmed bullish open — but the screenshot's "OI 10" was a bad feed value (true prior OI ≈15,670), so the trade was always size-below-OI. It was a desk closing/taking profit on an existing long-call position ahead of Q2 earnings, not piling in.
- AKAM 6/11 — $6M Dec-2028 $150 LEAP call: OI FELL 2,022 → 580 (Δ −1,442 ≈ the 1,600 traded). Flagged provisional intraday (size < OI); resolved to a close — a desk exited an existing LEAP, not a fresh 2.5-year bull bet.
💵 Big-Ticket Close
- GLD 6/11 — $35M deep-ITM $400 put: OI FELL 44,132 → 31,970 (Δ −12,162 ≈ the 12,592 traded). The day's biggest print was a hedge being unwound — a holder of deep-ITM puts banked a winner as gold sat near a monthly low. The "hedge-unwind" side we flagged, confirmed. $35M of capital out, not new bearish conviction.
✅ Confirmations — The Fresh, Defensive Positioning Opened
- DRAM 6/11 — aggressive $65 put sweep: OI ROSE 989 → 16,035 (Δ +15,046, even larger than the ≈9,959 swept) — more bears piled into the memory-ETF puts ahead of Micron's June 24 earnings.
- SMH 6/11 — $17M year-out $550 put: OI ROSE 127 → 2,027 (Δ +1,900 ≈ size). The semiconductor tail hedge opened.
- YPF 6/11 — $1.8M 2028 $50 put: OI ROSE 2 → 2,002 (Δ +2,000 = size). The long-dated Argentina tail hedge opened cleanly.
What changed in the post-resolution read
Pre-resolution Thursday PM: ≈$80.3M across 6 prints, framed as ≈$62M of hedges plus ≈$18M of bullish calls (AKAM, AMZN). Post-resolution Friday AM: the picture inverts — only ≈$27M was fresh money, all of it bearish/defensive (DRAM, SMH, YPF opened); ≈$53M was capital leaving existing positions (AKAM, AMZN, GLD all closed). Both "bullish" reads were exits.
Standing lesson: a "size ≫ OI" confident-open read is only as good as the OI number feeding it. AMZN's screenshot OI of 10 was wrong by three orders of magnitude — the real OI made it a size-below-OI print, and the next-day OI proved a close. Always verify a surprisingly tiny prior OI against the tape before calling a fresh open.
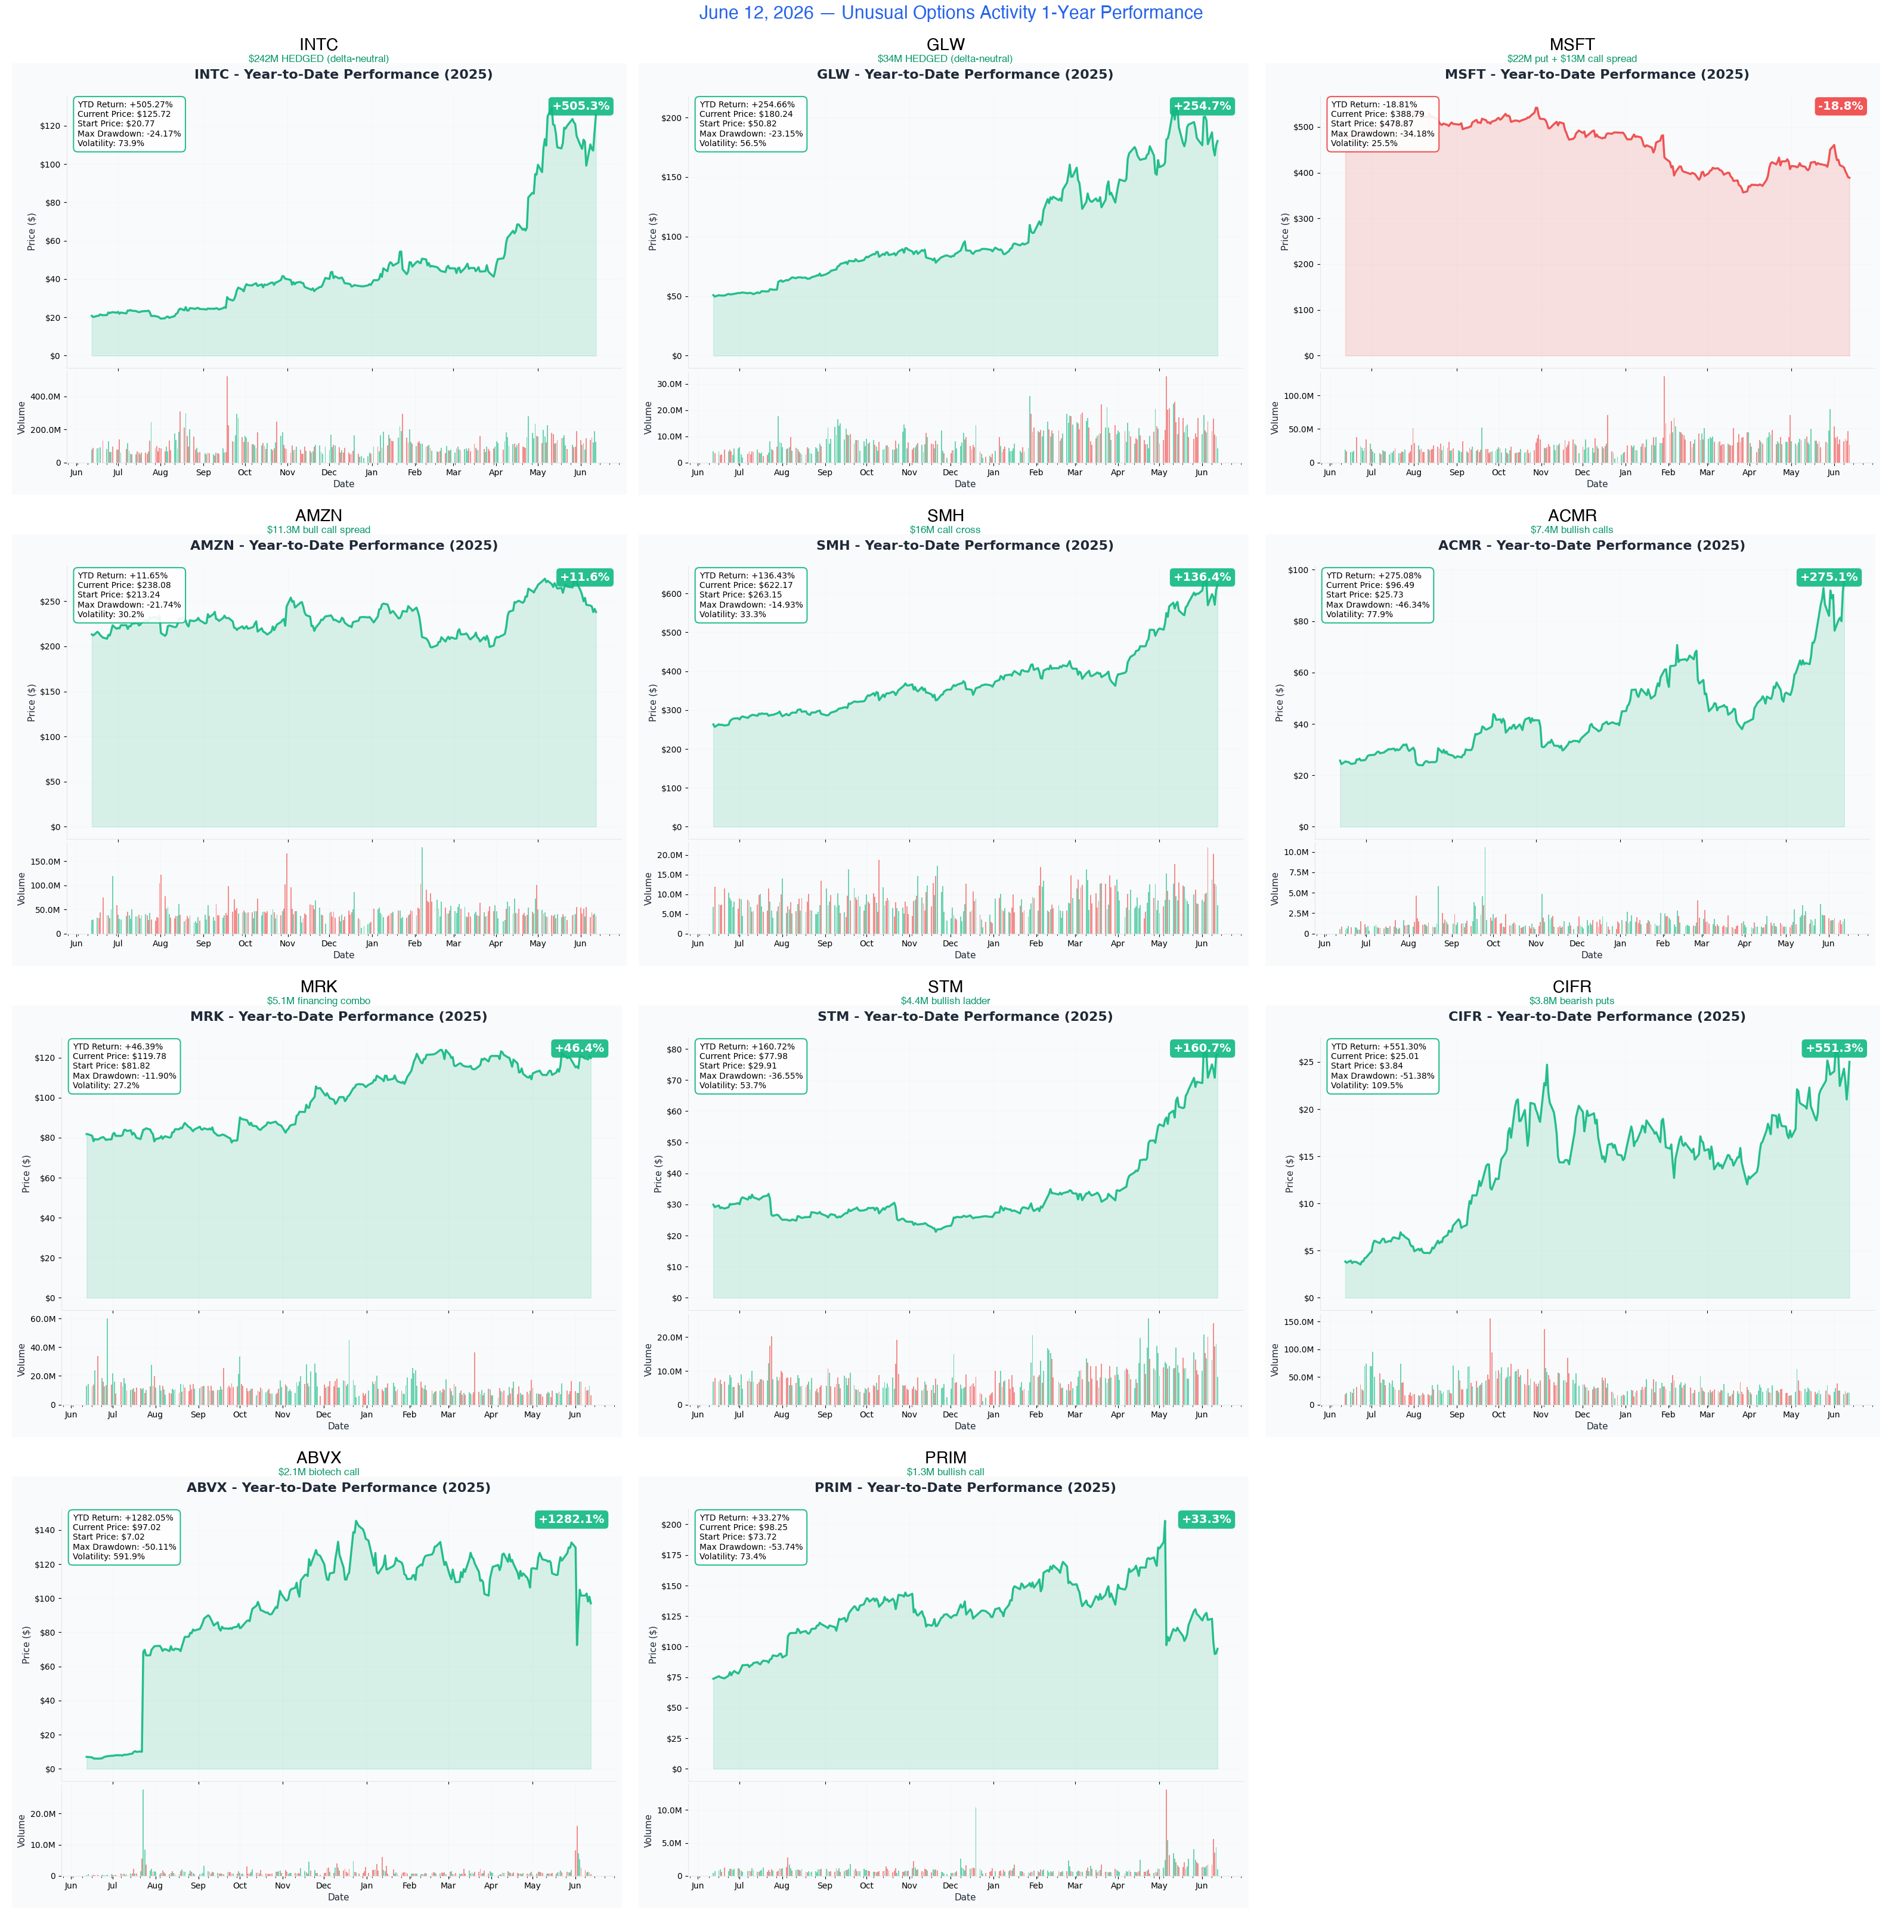
⚡ The Quick Read
- The $276M that isn't a bet (INTC + GLW): Both printed as deep-in-the-money call crosses and both were hedged with a short-stock block within seconds — delta-neutral by construction. A real bull buys at-the-money or out-of-the-money calls for leverage; you do not pay $242M for 0.79-delta calls and then short $625M of stock against them unless the goal is volatility / financing, not direction. Treat the headline numbers as plumbing, not conviction.
- The genuinely bullish directional flow (≈$60M): SMH ≈$16M $620 call cross into a catalyst-packed September; AMZN ≈$11.3M-net bull call spread ($270/$295) straddling Q2 earnings; ACMR ≈$7.4M and STM ≈$4.4M short-dated call ladders on red-hot semi names (both pure momentum — earnings land after expiry; STM's provisional $80C leg resolved as a confirmed open); PRIM ≈$1.3M data-center-builder call. MRK ≈$5.1M printed like a cautiously-bullish diagonal but next-day OI inverted it — the Sep $100C leg closed (not opened) and a Dec $105C short opened, so it was a de-risking / overwrite repositioning, not a bullish bet.
- The bearish / split prints: CIFR ≈$3.8M of June puts — a clean downside bet on a debt-heavy bitcoin miner with no revenue catalyst before expiry. MSFT is genuinely two-sided: a ≈$12.8M bull call spread AND a separate $22M deep-ITM put block cross — two desks, opposite views, same session.
- The biotech lottery: ABVX ≈$2.1M of December $100 calls — owning the late-Q4 obefazimod NDA-filing window, at eye-watering implied vol after a 43% one-day drop on a safety signal.
The tape's message: the biggest dollars today are hedged financing, and the real directional money is a measured bullish lean on semis/infrastructure plus a couple of pointed downside bets. Nothing here is a stampede — read the mechanism before the money.
👀 Today at a Glance
| Ticker | Net Premium | Expiration (Type) | Flow type & signal | Option Play | Direction / Meaning |
|---|---|---|---|---|---|
| INTC | $242M | Sep 2026 (Quarterly) | 🤝 block cross + 5.0M-share stock hedge | Deep-ITM $97.5 call, delta-hedged | ⚪ NON-DIRECTIONAL (synthetic put / financing) |
| GLW | $34M | Sep 2026 (Quarterly) | 🤝 block cross + 520K-share stock hedge | Deep-ITM $140 call, delta-hedged | ⚪ NON-DIRECTIONAL (synthetic put / financing) |
| MSFT | $22M put + $12.8M spread | Aug + Sep 2026 (Monthly/Quarterly) | 🤝 put block cross and multi-leg-auction call spread | $420 put + $450/$530 bull call spread | 🔴🟢 MIXED — bearish put + bullish call spread |
| SMH | $16M | Sep 2026 (Quarterly) | 🤝 block cross | $620 call (≈1.5% OTM) | 🟢 Bullish positioning (semis) |
| AMZN | $11.3M net | Aug 2026 (Monthly) | multi-leg auction | $270 long opened / $295 net-closed (roll down) | 🟢 Bullish — OI-resolved as a roll down (✅ $270 BTO, $295 net STC) |
| ACMR | $7.4M | Jun 2026 (Weekly/0DTE) | multi-leg auction | Bullish calls $86/$89/$100 | 🟢 Bullish (momentum, no catalyst in window) |
| MRK | $5.1M net | Sep + Dec 2026 (Quarterly/LEAP) | multi-leg options floor structure | Sep $100C closed / Dec $105C short opened | 🔄❗ INVERTED → neutral-to-mildly-bearish (de-risking / overwrite, not a bullish diagonal) |
| STM | $4.4M | Jun 2026 (Weekly/0DTE) | multi-leg auction | Bullish call ladder $75/$80/$82 | 🟢 Bullish (momentum, no catalyst in window) |
| CIFR | $3.8M | Jun 2026 (Weekly) | multi-leg auction | Long puts $23.5/$25.5 | 🔴 Bearish (debt/dilution, BTC weak) |
| ABVX | $2.1M | Dec 2026 (Quarterly/LEAP) | ⚡ lit | ATM $100 call | 🟢 Bullish (NDA-filing lottery, huge IV) |
| PRIM | $1.3M | Aug 2026 (Monthly) | multi-leg auction | $120 call (≈23% OTM) | 🟢 Bullish (data-center build-out) |
Net premium = long legs paid − short legs collected. ≈$362M printed, but ≈$276M (INTC + GLW) is delta-neutral financing with no directional content — the headline is plumbing, not conviction. Genuinely directional flow ≈$86M, leaning bullish on semis/infrastructure. Multi-leg auctions (AMZN, ACMR, MRK, STM, CIFR, PRIM, MSFT's calls) are facilitated worked orders, NOT block crosses; only INTC/GLW/SMH and MSFT's put are true single-leg crosses.
🔬 The Standouts, In Plain English
⚪ INTC — The $242M "Call Buy" That's Actually Delta-Neutral
A desk crossed 63,500 Sep $97.5 calls for $242M — the day's giant headline. But 8 seconds later a 5,000,000-share short-stock block printed at $125.00, and 63,500 × 100 × 0.79 delta ≈ 5.02M shares ≈ that block. The delta is cancelled. What's left is a synthetic long put / financing-conversion — a hedged volatility/financing position, not a bet that Intel goes up. The ≈$62.7M of time value is the real cost of the structure. A genuine bull would buy cheap out-of-the-money calls for leverage, not pay up for 0.79-delta calls and short the delta away. Intel itself is a fascinating story (foundry turnaround, government/Nvidia stakes, BofA's June 11 double-upgrade to Buy, $135, earnings July 23) — but this trade doesn't express a direction on it.
⚪ GLW — Same Playbook, $34M
Corning's print is the identical pattern: 6,700 Sep $140 deep-ITM calls ($34M) crossed, then a 520,000-share short-stock block at $176.50 ≈ the 6,700 × 100 × 0.78 delta. Delta-neutral, synthetic-put/financing — not a bullish bet on the AI optical-fiber boom that has Corning up ≈90%+ on the year. Two giant "call buys," zero net directional exposure between them.
🔴🟢 MSFT — Two Desks, Opposite Views, Same Day
The genuinely split print. In the morning, a ≈$12.8M-net bull call spread ($450/$530 Sep) was worked via multi-leg auction — bullish if MSFT rallies into autumn. In the afternoon, a different desk crossed a $22M block of deep-ITM $420 August puts — downside protection. With Q4 FY2026 earnings on July 28 sitting inside both windows and the ≈$190B capex overhang still pressuring the stock (≈14% off its high), the options market is openly divided. Don't read either leg as "the" MSFT signal.
🟢 SMH / AMZN — The Cleanest Bullish Directional Reads
SMH ≈$16M $620 call cross sits ≈1.5% above spot, right at the first gamma-resistance wall, into a dense September (NVDA's S&P 500 inclusion June 22, Micron June 24, NVDA earnings Aug 26). AMZN ≈$11.3M-net Aug $270/$295 print was a bullish bet into Q2 earnings ≈July 30 and Prime Day June 23–26; next-day OI showed the $270 leg opened (BTO) while the $295 leg net-closed (STC), so it reads as a bullish roll down to a higher-delta strike rather than a clean capped spread — directional read unchanged.
🟢 ACMR / STM — Momentum Ladders With a Catch
Both are short-dated bullish call ladders on semis that have tripled-ish YTD — ACMR ≈$7.4M ($86/$89/$100) after Roth's $70→$100 target hike, STM ≈$4.4M ($75/$80/$82) after it nearly doubled its 2026 data-center revenue target to ≈$1B. The catch: both companies' earnings land after these options expire, so these are pure momentum/positioning bets with fast theta — not earnings plays.
🔴 CIFR — The Day's Clean Bearish Bet
≈$3.8M of June $23.5/$25.5 puts (no short leg) on a bitcoin miner carrying $5.2B+ debt with an $810M notes deal closing June 15, no AI revenue until August, and BTC down to ≈$63K. The risk to the bet: CIFR has a habit of gapping +20–30% on surprise hyperscaler-deal headlines, and these puts decay fast over two weeks.
📅 Upcoming Catalysts — Mind the Gap Between the Event and the Expiration
| Ticker | Next Catalyst (date) | Option Expiration | Catalyst inside the option's life? |
|---|---|---|---|
| CIFR | $810M notes close Jun 15 · no earnings before expiry | Jun 26, 2026 | ⚠️ Financing event yes; no earnings catalyst |
| ACMR | Q2 earnings ≈Aug 12 | Jun 12 / Jun 18, 2026 | ❌ No — earnings land after expiry (momentum only) |
| STM | Q2 earnings ≈Jul 23 | Jun 18, 2026 | ❌ No — earnings after expiry (momentum only) |
| SMH | NVDA S&P inclusion Jun 22 · Micron Jun 24 · NVDA earnings Aug 26 | Sep 18, 2026 | ✅ Yes — multiple |
| AMZN | Prime Day Jun 23–26 · Q2 earnings ≈Jul 30 | Aug 21, 2026 | ✅ Yes — straddles earnings |
| INTC | Q2 earnings Jul 23 | Sep 18, 2026 | ✅ Yes (but the trade is non-directional) |
| MSFT | Q4 FY26 earnings Jul 28 | Aug 21 (put) / Sep 18 (calls) | ✅ Yes — inside both |
| PRIM | Q2 earnings ≈Aug 3 | Aug 21, 2026 | ✅ Yes |
| GLW | Q2 earnings ≈Aug 4 | Sep 18, 2026 | ✅ Yes (but the trade is non-directional) |
| MRK | PDUFA Jun 19 / Aug 17 / Oct 10 · earnings ≈late Jul | Sep 18 / Dec 18, 2026 | ✅ Yes — dense calendar |
| ABVX | obefazimod U.S. NDA filing ≈late Q4 2026 | Dec 18, 2026 | ✅ Yes — the whole thesis |
🧑🤝🧑 For Four Kinds of Traders
🎰 The YOLO Trader. The short-dated semi ladders (ACMR, STM) are the adrenaline plays — but both have no earnings catalyst before expiry, so you're betting purely on momentum continuing, against fast theta. ABVX is a true lottery ticket: a December biotech call at ≈28%-of-spot premium, where a single safety-data headline can double it or zero it. Size these as money you can fully lose. And whatever you do, don't chase the INTC/GLW "call buys" as bullish — you'd be buying the hedged side of someone's financing trade.
📈 The Swing Trader. AMZN's defined-risk bull call spread is the cleanest swing setup — known risk (≈$11.3M max loss), known catalyst (July 30 earnings), known cap ($295). SMH gives you broad semi-beta into a packed September with the $620 strike at the gamma wall. Define risk to the implied move and respect the June-5-style fragility the sector just showed.
💰 The Premium Collector. Note the MSFT two-sided flow: a bull call spread AND a $22M put on the same name means the market is pricing genuine two-way uncertainty into July 28 — elevated IV across the board. That's an environment to sell defined-risk premium on names you'd happily own, not to go naked into binaries like ABVX or the 0DTE semi ladders.
🌱 The Beginner. Today's lesson is the most valuable one in options flow: a giant "BUY CALL" headline can be the opposite of bullish. INTC's $242M and GLW's $34M call buys were each immediately hedged with a short-stock block — the desk cancelled the delta, leaving a volatility/financing position with no directional view. Also learn the difference between a 🤝 block cross (a pre-arranged deal with a known counterparty — INTC, GLW, SMH, MSFT's put) and a multi-leg auction (a worked spread exposed for price improvement — AMZN, ACMR, MRK, STM, CIFR, PRIM, MSFT's calls). Neither is an urgent lit sweep. Mechanism first, money second.
⚠️ Risk & Patience — Read This Before You Trade Any of It
Unusual options activity is a research starting point, not a signal to copy. Today specifically:
- The two biggest prints (INTC, GLW) are hedged and non-directional. Copying them as "bullish call buys" would put you on the wrong side of a financing trade. The dollar size tells you nothing about direction here.
- Block crosses and auctions have a known counterparty. For every headline, someone informed took the other side. A cross/auction is a negotiated deal, not a one-way conviction stampede.
- Momentum bets without a catalyst (ACMR, STM) bleed theta fast. Their earnings land after expiry; you're paying for time you may not get paid back for.
- Biotech and crypto-miner options (ABVX, CIFR) carry binary, gap risk in both directions. ABVX can move 40%+ on a single data point; CIFR has gapped 20–30% on surprise deal news against exactly this kind of put. Never bet money you can't afford to lose on a single binary.
What the tape cannot tell us: the trader's identity, the full intent, the sign of pre-existing open interest, or (without the equity tape) a hidden stock hedge. Several of today's reads were only possible because we checked the stock tape for the hedge. Treat every read as a hypothesis to verify, and check tomorrow's open interest.
Not investment advice. Options carry substantial risk of loss. Past unusual activity does not predict future returns. Always do your own research and manage position size.